Why focus on the sticker price of a new car when the only figure that actually impacts your lifestyle is the amount that hits your bank account every second Wednesday? Most Australians find the technical jargon surrounding salary packaging, like Fringe Benefits Tax or the Employee Contribution Method, deeply confusing. You aren’t alone if you’ve felt a sense of dread that hidden costs might swallow your supposed savings. It’s difficult to feel confident in a financial decision when you’re unsure how it affects your HECS debt or your net disposable income.
This guide provides the clarity you need by explaining how a novated lease calculator after tax models your real-world outcome. We’ll show you exactly how your fortnightly pay changes under the 2026-27 tax brackets, including the 15% rate for mid-tier earners and the 2% Medicare Levy. You’ll learn why the window for full EV FBT exemptions is closing in March 2027 and how to determine if a lease truly beats a standard car loan. By the end of this breakdown, you’ll have a transparent view of your future take-home pay, allowing you to secure your next vehicle with absolute financial certainty.
Key Takeaways
- Understand why your net disposable income is the only metric that matters and how the Employee Contribution Method (ECM) can be used to offset Fringe Benefits Tax.
- Learn how to compare the total cost of ownership against a personal car loan, including the GST savings available on the vehicle’s purchase price and running costs.
- Discover how to use a novated lease calculator after tax to accurately model your savings based on the latest 2026-27 tax brackets and your specific salary.
- Realise why a digital estimate is just the starting point and how professional quotes provide a precise look at fleet discounts and competitive effective interest rates.
- Identify the specific data you need to collect before requesting a quote to ensure your financial model accounts for all variables, including HECS/HELP obligations.
Why Your After-Tax Take-Home Pay is the Only Number That Matters
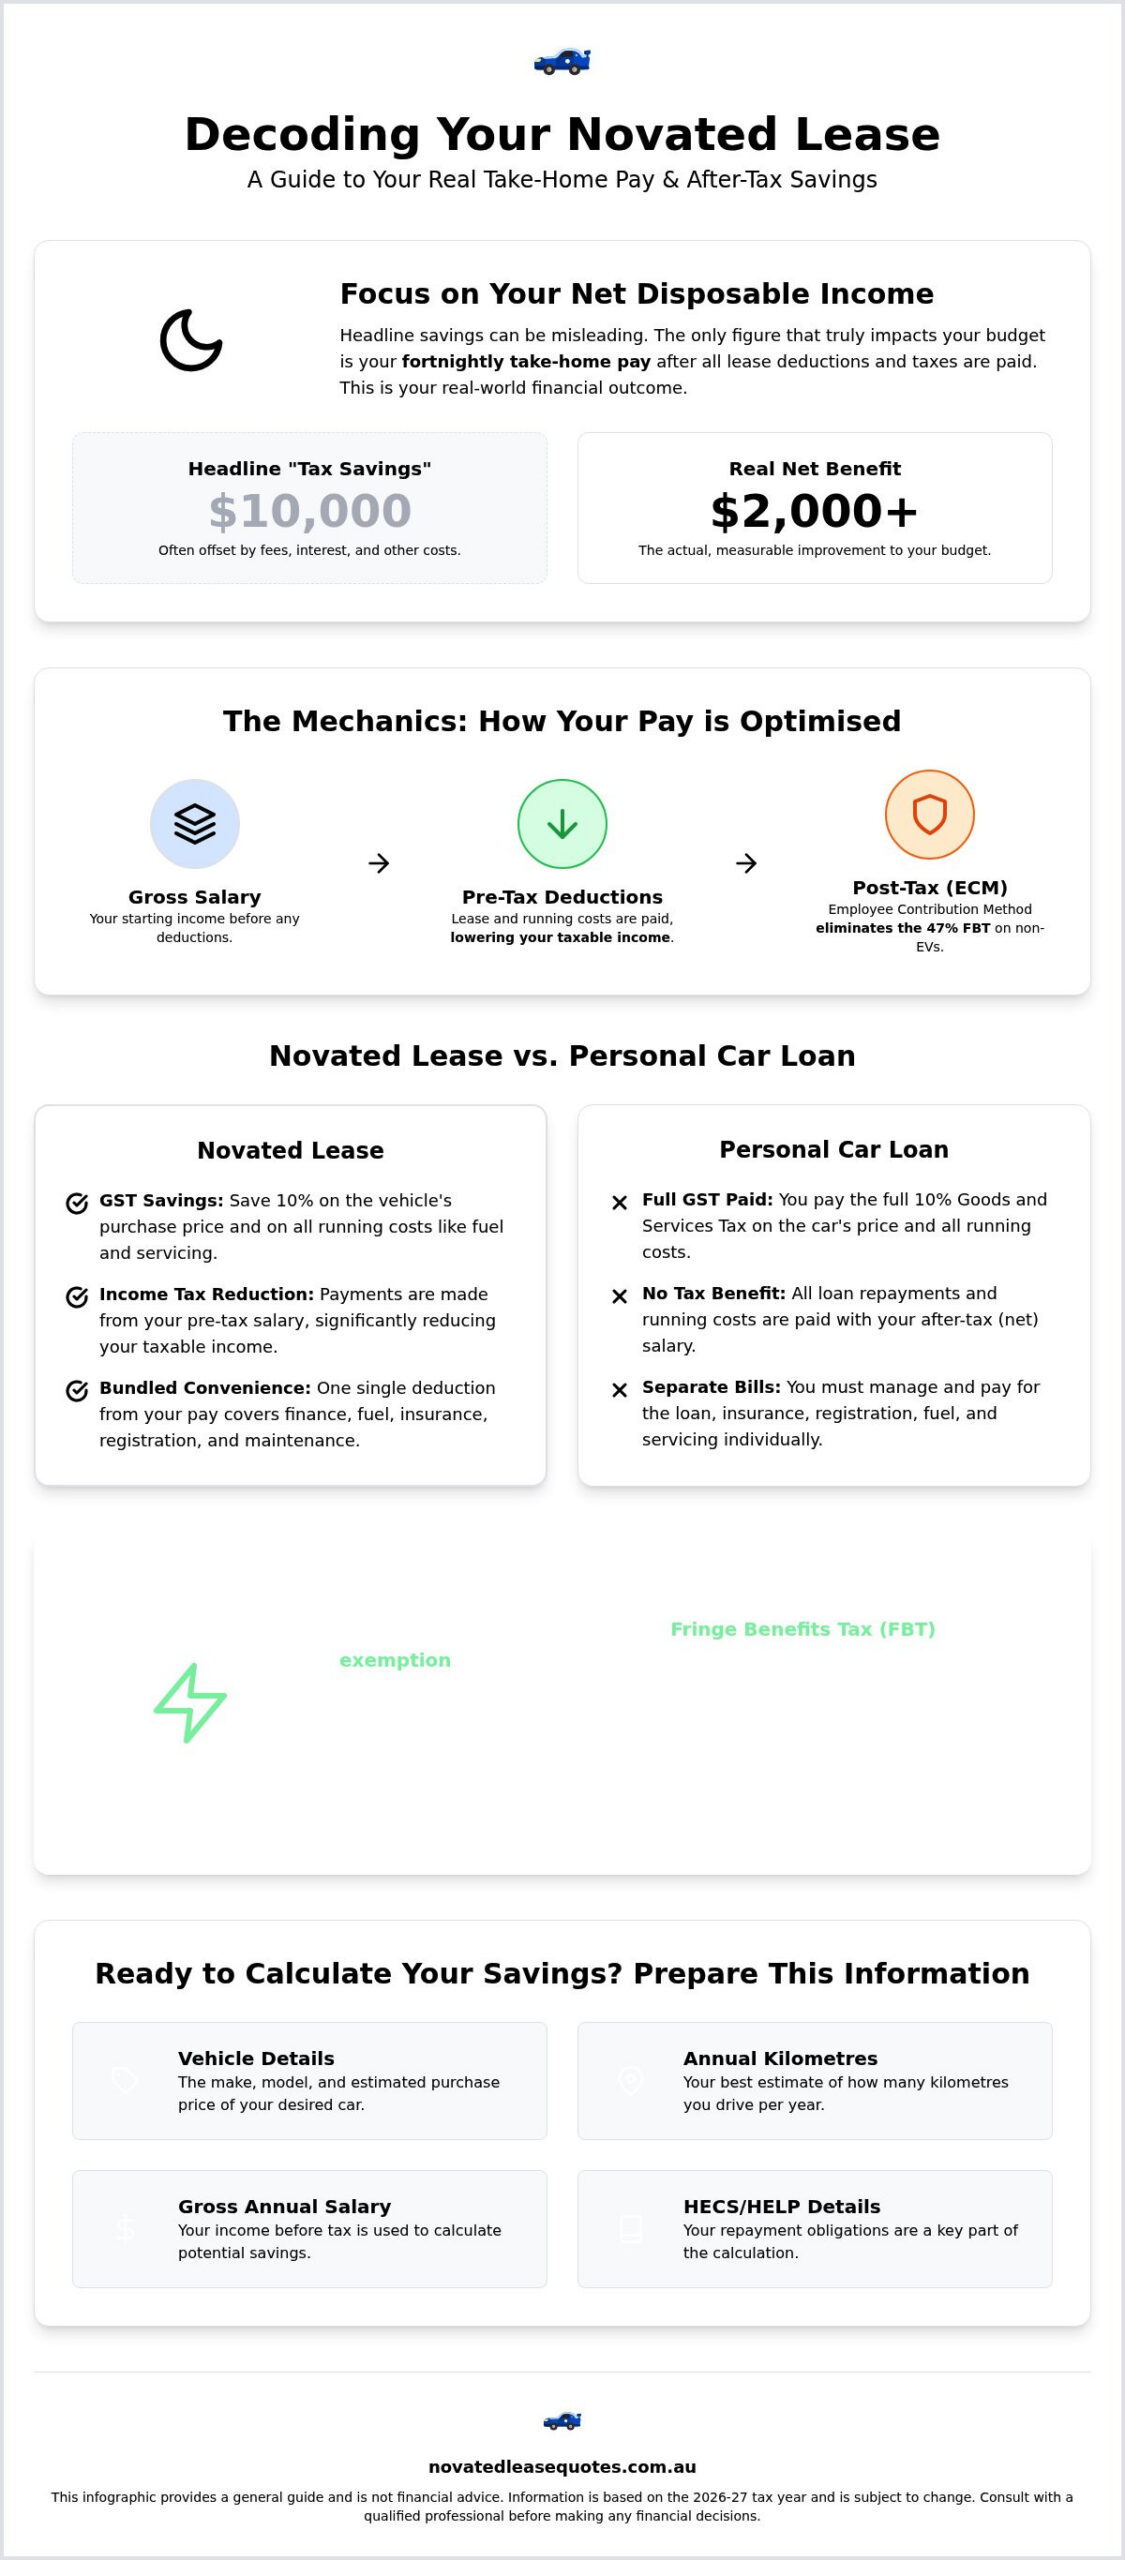
Marketing brochures often lead with eye-watering figures like “Save $15,000 in tax.” While these numbers are technically accurate, they don’t tell the full story of your financial health. To understand the true value of what a novated lease is, you must look past the headline tax savings and focus on your net disposable income. This is the actual amount of money that hits your bank account every fortnight after your employer has deducted lease costs and tax.
A reliable novated lease calculator after tax should provide a clear “before and after” view of your pay slip. If you currently take home $3,500 a fortnight and a lease reduces that to $3,200, but covers all your fuel, insurance, and maintenance, your net position has likely improved. However, if the drop in pay is larger than your current car expenses, the lease might not be the right choice. Net disposable income is the only metric that accounts for the reality of your household budget.
The Difference Between Pre-Tax Savings and Post-Tax Reality
Salary packaging works by using a portion of your pre-tax salary to pay for car expenses. This reduces your taxable income, meaning you pay less to the ATO. It’s a powerful tool, but it’s important to remember that these deductions also reduce your gross pay. The goal is to ensure the tax you save is significantly higher than the costs of the lease itself.
One of the most immediate advantages is the GST saving on the purchase price. Because the financier buys the car, you avoid paying the 10% GST on the vehicle’s price, up to the luxury car tax limit. Regarding ongoing expenses, your employer generally claims back the GST on running costs and passes that credit back into your lease account to further reduce your expenses.
Why Headline Savings Often Hide the Real Cost
It’s common for a $10,000 headline tax saving to result in a much smaller net benefit, sometimes as low as $2,000 over the life of the lease. This happens when the “savings” are offset by high effective interest rates, monthly management fees, or overpriced insurance products bundled into the package. Without a transparent breakdown, these costs remain invisible until you see your reduced pay slip.
To avoid these traps, you need to model your specific situation. Using a novated lease calculator allows you to input your exact salary and expected running costs. This provides a realistic estimate of your novated lease calculator after tax outcome, ensuring that the convenience of salary packaging doesn’t come at the expense of your actual take-home pay.
Pre-Tax vs Post-Tax: Understanding the Employee Contribution Method (ECM)
Fringe Benefits Tax (FBT) is a 47% levy applied to benefits provided to employees outside of their regular salary. When you lease a petrol or diesel car through your employer, the ATO views this as a taxable benefit. Without a specific strategy, the cost of this tax could easily outweigh any potential savings. This is where the Employee Contribution Method (ECM) becomes essential. By paying a portion of your car’s running costs from your post-tax salary, you reduce the taxable value of the benefit to zero, effectively “wiping out” the FBT liability.
This approach differs significantly from the EV novated lease Australia framework. For eligible electric vehicles below the luxury car tax threshold, the government currently provides a full FBT exemption. This means you don’t need to use the ECM for these cars, allowing you to pay for the entire lease and all running costs from your pre-tax salary. For internal combustion engine (ICE) vehicles, however, a mix of pre-tax and post-tax payments remains the standard way to optimise your financial outcome.
How ECM Affects Your Pay Slip
A typical pay slip for a non-EV novated lease shows two distinct deductions. The first is a pre-tax deduction that reduces your gross salary, which in turn lowers the amount of income tax you pay. The second is a post-tax contribution. While using “net” money might feel more expensive at first glance, it’s a strategic move. Every dollar you contribute from your after-tax pay reduces the taxable value of the car by the same amount. For most professionals, particularly those in the 30% or 37% tax brackets, this is far cheaper than paying the 47% FBT rate.
A novated lease calculator after tax is designed to model this specific split. It calculates the exact amount of post-tax contribution required to eliminate FBT based on the car’s purchase price. This ensures you aren’t overpaying from your net income while still capturing the maximum possible tax relief on your fuel, insurance, and servicing costs. If you want to see how this split applies to your specific salary, you can compare current lease options to find the most efficient structure.
The 2026 Outlook for FBT-Exempt Vehicles
As we move into the 2026-27 financial year, the rules for FBT exemptions are becoming more targeted. The full FBT exemption for eligible electric vehicles is currently legislated to continue until 31 March 2027 for vehicles below the luxury car tax threshold. After this date, the exemption transitions to a partial discount for many models. This time-sensitive change makes it vital to use a novated lease calculator after tax that is updated for these future rules.
Model accuracy is especially important for those considering plug-in hybrids, which have already seen changes to their exemption status. Because these rules are complex and depend on the vehicle’s value and delivery date, relying on generic estimates is risky. Obtaining specialised novated lease quotes is the most reliable way to ensure your after-tax modelling accounts for the latest ATO thresholds and FBT legislation.
Comparing the Net Outcome: Novated Lease vs. Personal Car Loan
A personal car loan might appear more attractive on paper due to a lower advertised interest rate, but this perspective is often too narrow. When you take out a standard loan, you pay for the vehicle using your after-tax income. This means every dollar spent has already been taxed at your marginal rate, which could be as high as 47% including the Medicare Levy. In contrast, a novated lease allows you to use a combination of pre-tax and post-tax funds, significantly reducing the total cost of ownership over a typical three to five year term.
The most immediate advantage is the GST saving. When you purchase a vehicle through a personal loan, you pay the full retail price including 10% GST. With a novated lease, the financier effectively claims the GST back, which reduces the amount you need to finance by thousands of dollars, up to the luxury car tax limit. Using a novated lease calculator after tax helps you see how this day-one discount, combined with ongoing tax relief, usually outweighs the impact of a slightly higher interest rate compared to a bank loan.
The Power of Bundled Running Costs
One of the most significant benefits of salary packaging is the ability to pay for everyday expenses with pre-tax dollars. For most professionals, paying for fuel, tyres, and servicing with pre-tax money provides an instant discount of 30% to 45%, depending on your tax bracket. This “piggy bank” approach stabilises your monthly budget because all costs are smoothed out into a single, predictable deduction from your pay slip. You aren’t hit with a massive bill when four new tyres are due; the funds are already waiting in your lease account.
Understanding novated lease running costs is vital for an accurate comparison. While a personal loan only covers the car’s purchase price, the lease covers the entire ecosystem of vehicle ownership. This comprehensive structure ensures your novated lease calculator after tax results reflect your actual lifestyle costs rather than just a finance repayment.
Residual Value: The Final After-Tax Piece
Every novated lease includes a residual value, also known as a balloon payment, which is a lump sum required by the ATO at the end of the term. This amount is based on the age of the vehicle and must be paid with post-tax dollars. While some see this as a hurdle, it’s actually a strategic component of the lease. It keeps your fortnightly repayments lower than a principal-and-interest loan, allowing you to maintain better cash flow throughout the lease period.
The real advantage appears when you decide to sell or trade the vehicle. If you maintain the car well and sell it for more than the residual value, any profit you make is generally tax-free. This potential for a “tax-free windfall” is a major factor that often tips the scales in favour of leasing over traditional finance. It’s the final piece of the puzzle that proves why the net outcome is more important than the interest rate alone.
How to Accurately Model Your Savings for 2026
Building a precise financial model requires more than just a basic salary input. A robust novated lease calculator after tax must integrate the specific tax settings for the 2026-27 financial year, such as the 15% rate for income up to $45,000 and the 30% bracket for earnings up to $135,000. To get an accurate result, start by determining your total taxable income, ensuring you include any regular bonuses or commissions that might push you into a higher tax bracket. While annual kilometres no longer dictate the FBT rate for petrol cars, they remain the primary driver for your fuel, tyre, and maintenance budgets.
The next stage involves comparing vehicle types side-by-side. The current landscape offers a unique advantage for electric vehicles, but the window for the full FBT exemption on higher-priced models is closing on 31 March 2027. If you’re considering a plug-in hybrid or a high-spec EV, your model must account for these time-sensitive legislative shifts. Don’t forget to factor in the 2% Medicare Levy and any applicable Medicare Levy Surcharge. Once you have these basics, use a novated lease comparison to test how different provider fees and effective interest rates change your fortnightly outcome.
The HECS/HELP and Childcare Trap
Salary packaging a vehicle creates a Reportable Fringe Benefit Amount (RFBA) on your annual payment summary. While you don’t pay income tax on this amount, it’s used to calculate other government obligations. A higher RFBA can lead to an increase in your compulsory HECS/HELP repayments or a reduction in your Childcare Subsidy entitlements. Before committing to a lease, it’s vital to calculate your adjusted taxable income. This ensures your after-tax take-home pay isn’t unexpectedly reduced by higher debt repayments at tax time. If you’re unsure how these variables interact, you can request a tailored quote to see the exact impact on your net position.
Choosing the Right Lease Term for Your Budget
The duration of your lease significantly dictates your fortnightly cash flow. A one-year lease will result in a much higher deduction from your pay slip but minimizes the total interest paid over the life of the agreement. Conversely, a five-year lease offers the lowest impact on your immediate take-home pay, though you’ll pay more in interest charges over the longer term. Selecting the right term depends on whether you prioritize monthly lifestyle cash flow or the lowest possible total cost of ownership. It’s often helpful to seek professional advice to determine which term aligns with your broader financial goals and vehicle replacement cycle.
Get Tailored Quotes to Confirm Your Real-World Savings
Using a novated lease calculator after tax is the smartest way to begin your research. It gives you a baseline for your budget and helps you understand how the 2026 tax rules apply to your specific salary. However, a digital tool cannot account for the live variables of the Australian automotive market. Real-world quotes take into account specific dealer discounts, current stock availability, and fleet pricing that isn’t available to the general public. These factors can significantly lower the total amount you need to finance, which further increases your fortnightly benefit.
Novated Lease Quotes simplifies this complex process by acting as an expert facilitator. We focus on transparency and efficiency, ensuring you don’t just get a generic estimate but a precise financial roadmap. By connecting you with multiple providers, we help you find the most competitive effective interest rates and the most favourable lease structures tailored to your professional situation. This pragmatic approach removes the guesswork and ensures your final decision is based on verified data rather than marketing projections.
Why Multiple Quotes are Essential
It’s a common misconception that all leasing companies are the same. In reality, interest rates and procurement power vary wildly between providers. Even if your employer has a preferred provider, they might not offer the best market rate or the most transparent fee structure. Comparing multiple quotes is the only way to verify that your headline tax savings aren’t being eroded by hidden management costs. Our comparison service allows you to benchmark different offers side-by-side, giving you the data needed to make an objective decision. You wouldn’t settle for the first car you see on the lot; your finance should be treated with the same level of scrutiny.
Your Next Steps to Salary Packaging Success
Moving from curiosity to commitment is a structured process. First, use a novated lease calculator after tax to establish your baseline. Second, compare those results against professional quotes to see the impact of fleet discounts and competitive interest rates. Finally, commit to the structure that helps maximise your net disposable income. The goal is simple: you want to drive the car you need while keeping as much of your hard-earned salary as possible. Our proactive team is ready to help you navigate these choices with clarity and confidence. Start your journey today by requesting a personalised quote comparison and take control of your financial future.
Secure Your Financial Future with Data-Driven Decisions
Navigating salary packaging doesn’t have to be a source of stress. By focusing on your net disposable income rather than inflated marketing claims, you ensure your next vehicle purchase supports your lifestyle instead of straining it. It’s clear that the only metric that truly matters is the change to your fortnightly pay slip. Whether you’re leveraging the current EV FBT exemptions or using the Employee Contribution Method to offset costs for a petrol vehicle, accuracy is vital.
A high-quality novated lease calculator after tax provides the foundation, but real-world savings are confirmed through competitive market comparisons. We specialise in expert 2026 tax modelling and independent assessments that account for the latest ATO thresholds and HECS obligations. Our service streamlines the path to your new car by connecting you with multiple Australian providers to find the lowest effective interest rates.
Ready to see your actual take-home pay? Get a Tailored Novated Lease Quote Comparison Today and receive a no-obligation savings assessment. You’ve done the research; now it’s time to maximise your hard-earned salary with absolute confidence.
Frequently Asked Questions
Does a novated lease affect my HECS/HELP repayments?
Yes, it definitely does. While salary packaging reduces your taxable income, it generates a Reportable Fringe Benefit Amount (RFBA). The ATO includes this RFBA when determining your repayment income for HECS/HELP debts. Consequently, your compulsory repayment percentage may increase, slightly reducing your fortnightly take-home pay. It’s essential to account for this in a novated lease calculator after tax to avoid an unexpected bill when you lodge your annual tax return.
What is the Employee Contribution Method (ECM) and why is it used?
The Employee Contribution Method (ECM) involves paying a portion of your vehicle’s running costs from your post-tax salary. This strategy is primarily used for petrol and diesel cars to reduce the taxable value of the fringe benefit to zero. By doing so, you effectively eliminate the 47% Fringe Benefits Tax (FBT) liability. This often results in a better financial outcome than paying for the entire lease from your pre-tax income alone.
Is an EV novated lease still worth it in 2026?
Yes, an EV lease remains highly effective in 2026. The full FBT exemption for eligible electric vehicles below the luxury car tax threshold is currently legislated to continue until 31 March 2027. Even as exemptions transition to partial discounts for some models after this date, the combination of GST savings on the purchase price and paying for electricity from your pre-tax salary continues to provide a significant advantage over traditional car loans.
How does a novated lease impact my tax return at the end of the year?
A novated lease generally doesn’t result in a large tax refund or debt because the tax benefits are applied to your pay slip throughout the year. Your employer reduces your PAYG withholding based on your lower taxable income. While a Reportable Fringe Benefit Amount (RFBA) will appear on your payment summary, it isn’t included in your taxable income. It is, however, used to assess HECS repayments and some government benefits.
Can I include a used car in an after-tax calculator?
You can certainly include a used car in your calculations. Most leasing providers allow you to package a used vehicle, provided it meets specific age and kilometre requirements at the start of the lease. While you don’t save GST on the purchase price if buying from a private seller, you still benefit from paying for insurance, fuel, and servicing with pre-tax dollars. This makes a used car a viable budget-friendly option.
What happens to my take-home pay if I change jobs mid-lease?
If you change jobs, your lease becomes “de-novated” and the responsibility for the monthly payments temporarily shifts entirely to you. These payments must be made from your after-tax income until you find a new employer willing to take over the novation agreement. Most modern employers are open to this, as it costs them nothing to facilitate. Once the new agreement is signed, your tax-effective deductions will resume as normal.
Is the residual value (balloon payment) paid from pre-tax or after-tax income?
The residual value, or balloon payment, must be paid using after-tax income at the end of your lease term. The ATO sets minimum residual percentages based on the lease duration to ensure the arrangement remains a genuine lease rather than a disguised purchase. When the lease ends, you can pay the residual to own the car, trade it in for a new model, or refinance the remaining amount into a new lease.
Does salary packaging a car affect my borrowing capacity for a mortgage?
Mortgage lenders view a novated lease as a financial commitment, similar to a personal loan. The deduction from your pay slip is factored into your debt-to-income ratio, which can slightly reduce your maximum borrowing capacity. However, lenders also recognise that the lease covers your major vehicle running costs. Providing a clear breakdown from a novated lease calculator after tax can help your bank understand your true net disposable income.


