What if your next vehicle purchase could actually increase your monthly take-home pay instead of draining it? While most people view a car as a simple expense, smart professionals use it as a strategic income-shifting tool. If you’ve ever wondered how does salary packaging a car work, it’s essentially a three-way agreement between you, your employer, and a financier that allows you to pay for a car and its running costs using your pre-tax salary.
It’s completely normal to feel overwhelmed by the jargon of Fringe Benefits Tax, luxury car thresholds, and the anxiety of a looming balloon payment at the end of the term. You want to be certain you aren’t being locked into a rigid deal that benefits the provider more than your bank account. This 2026 guide demystifies the entire process by breaking down the financial flow of a novated lease. We’ll provide a clear framework to help you compare quotes, model your savings with precision using a calculator, and ensure you’re maximising every possible cent of value from your salary. You will walk away with the confidence to choose a deal that truly fits your financial goals.
Key Takeaways
- Learn how does salary packaging a car work by understanding the three-way agreement that turns your vehicle into a powerful tax-saving tool.
- Discover how to save up to $6,353 in GST on your next car purchase while reducing your annual income tax through pre-tax deductions.
- Explore the 2026 FBT exemptions for electric vehicles and how they can significantly boost your take-home pay compared to traditional finance.
- Master the lease lifecycle, from accessing exclusive fleet discounting to navigating the final residual payment strategy.
- Understand why an independent comparison of quotes is the only way to avoid hidden fees and secure the most competitive interest rates.
Demystifying the Australian Novated Lease
Salary packaging a car is often shrouded in complex financial jargon, but at its heart, it is a straightforward arrangement known as a Novated lease. In the 2026 Australian market, this has shifted from being an exclusive executive perk to a standard tool for tax optimisation across almost every industry. Understanding how does salary packaging a car work starts with shifting your perspective. You are no longer viewing a vehicle as a simple monthly expense. Instead, you are treating it as a strategic asset that reduces your taxable income.
By using a portion of your pre-tax salary to cover lease payments and running costs, you effectively lower the gross income the ATO uses to calculate your tax debt. This can often push you into a lower tax bracket, leaving more money in your pocket at the end of each pay cycle. It is a pragmatic approach to car ownership that prioritises financial efficiency over traditional debt structures.
The Core Concept: Salary Sacrifice vs. Net Pay
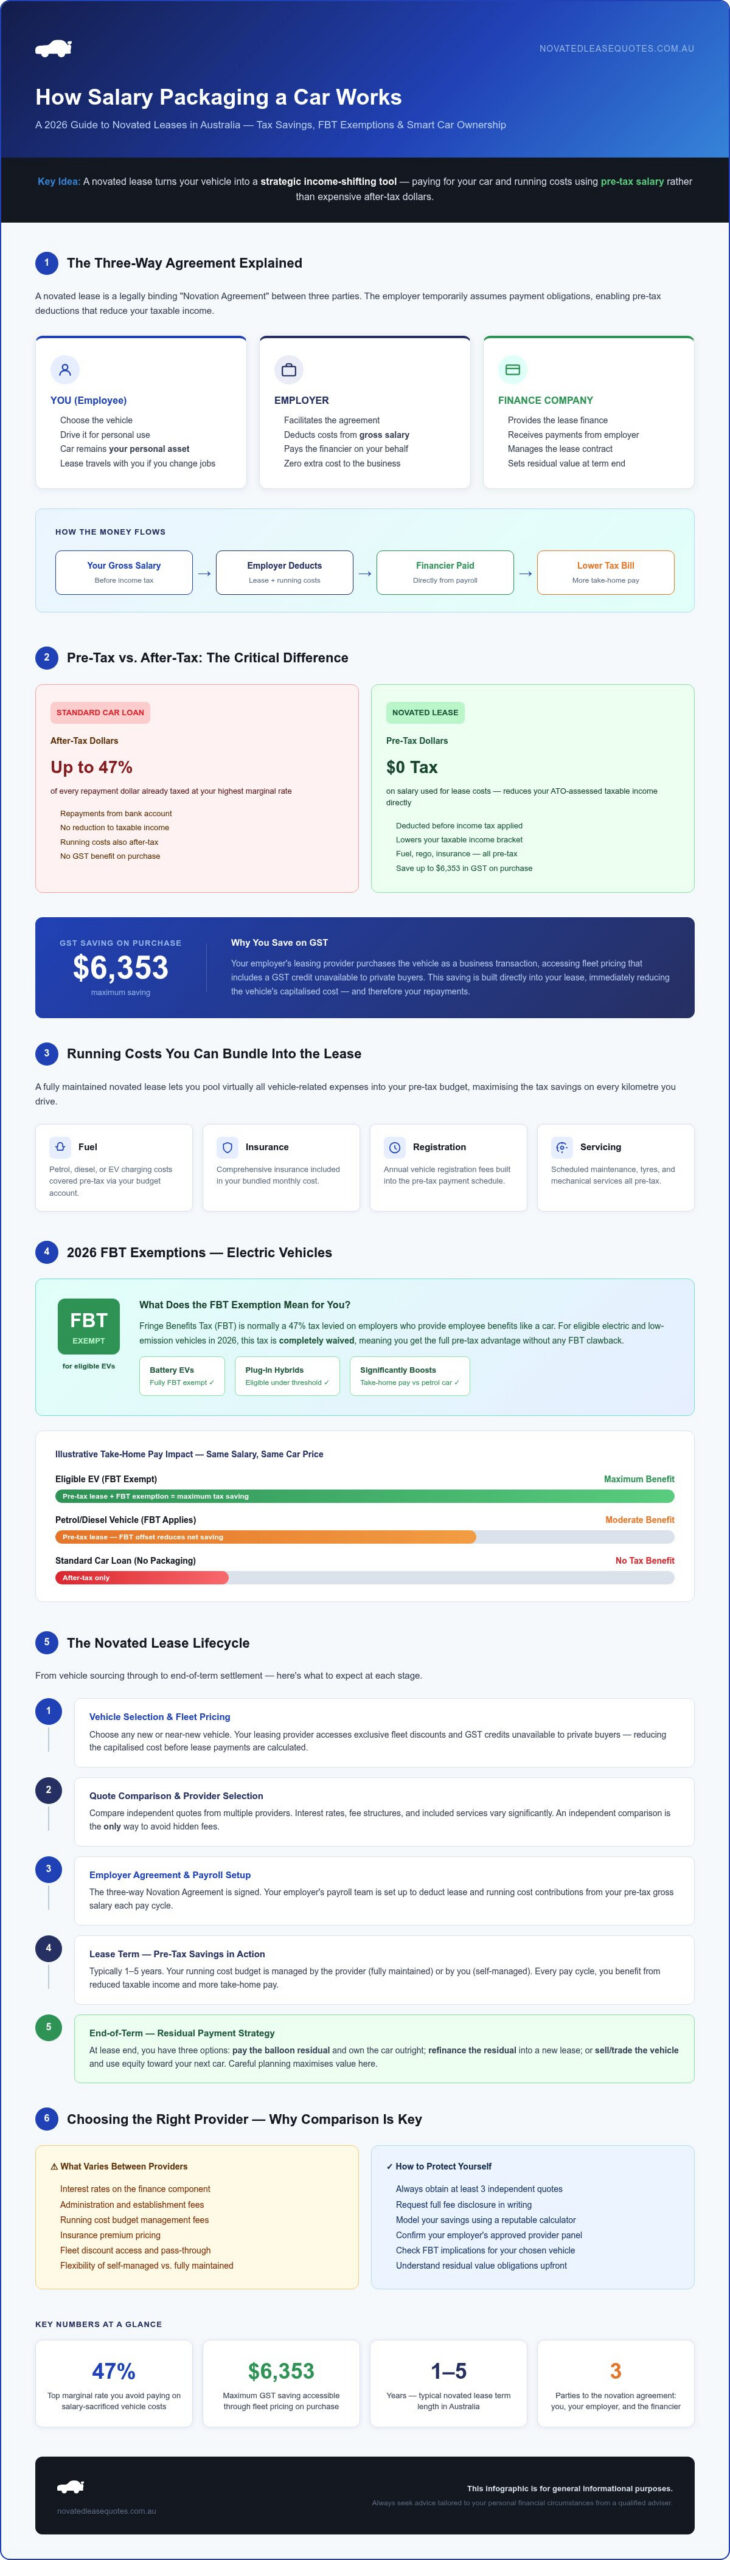
The fundamental difference between a novated lease and a standard car loan lies in which “bucket” of money you use. When you take out a traditional loan, you pay the lender from your bank account using “expensive” after-tax dollars. This is money that has already been taxed at your highest marginal rate, often as much as 47% for high earners. It is an inefficient way to fund a depreciating asset.
Salary sacrifice flips this model. Your employer deducts the lease costs directly from your payroll before income tax is applied. This “salary sacrifice” reduces your reportable income, which provides several immediate advantages:
- Lower Taxable Income: You only pay income tax on the remaining salary, not the full amount.
- Increased Purchasing Power: Because you use pre-tax dollars, your money goes significantly further than it would in a private sale.
- Bundled Expenses: Fuel, registration, insurance, and servicing are also paid from this pre-tax pool, maximising your savings on every kilometre driven.
Why Employers Support Salary Packaging
Many employees wonder why a company would agree to this three-way contract. The reality is that offering a novated lease costs the employer nothing, yet it adds immense value to a remuneration package. In the competitive 2026 job market, businesses use these benefits to attract and retain top talent without increasing their own overheads.
Modern Australian businesses rarely handle the paperwork themselves. They partner with specialised external providers who manage the administrative heavy lifting. This ensures the process is seamless for the payroll department while providing the employee with a sophisticated, tax-effective vehicle solution. It is a win-win scenario where the employer offers a high-value benefit and the employee enjoys a significant boost to their take-home pay.
The Three-Way Agreement: How the Mechanics Work
A novated lease is not a standard car loan; it is a unique legal structure involving three distinct parties. To understand how does salary packaging a car work, you must look at the dynamic relationship between the employee, the employer, and the finance company. While you choose the vehicle and drive it for personal use, the “Novation Agreement” is the legal engine that makes the tax savings possible. This contract temporarily transfers the payment obligation from you to your employer, allowing them to settle the lease costs directly from your gross salary.
Your employer acts as the essential facilitator in this arrangement. They make payments to the financier on your behalf, ensuring the financial flow remains consistent through your payroll. This process adheres to the Fair Work Ombudsman rules on pay deductions, which permit specific salary sacrifice arrangements when they provide a clear benefit to the employee. It is important to remember that although your employer makes the payments, the car remains your personal asset. If you change jobs, the novated agreement typically ends, and the lease travels with you to your next workplace.
The Role of the Leasing Provider
Leasing providers act as the specialised middleman, organising everything from the initial finance to insurance and ongoing running costs. A novated lease is a three-party contract that allows an employee to lease a vehicle while the employer assumes the payment obligations from pre-tax salary. You can choose between a “fully maintained” lease, where the provider manages all servicing and fuel costs via a budget, or a “self-managed” option if you prefer more hands-on control. Because fees and interest rates can differ between providers, it is often wise to compare multiple novated lease quotes to ensure you are getting the most efficient deal.
What Happens During the Lease Term?
Once the lease is active, the process is largely automated and requires very little effort from you. Your employer deducts a set amount from your payroll each cycle, which is then sent to a “clearing account” managed by the leasing provider. This account holds your funds to pay for the lease and any bundled running costs like registration, tyres, or insurance. You receive monthly statements that offer full transparency, allowing you to track your spending against your allocated budget. This “set and forget” nature is one of the primary reasons why salary packaging a car is so popular; it removes the administrative burden of ownership while keeping your financial optimisation on track.
Calculating the Savings: Tax, GST, and FBT Exemptions
To understand how does salary packaging a car work, you must look at the three pillars of financial optimisation: Income Tax, GST, and Running Costs. By shifting these expenses from your net pay to your gross salary, you create a tiered savings effect that traditional finance simply cannot match. This arrangement essentially allows you to fund your lifestyle using money that would otherwise be sent to the ATO as income tax.
The most immediate win is the GST exemption. When you source a vehicle through a novated lease, you do not pay GST on the purchase price, which can save you up to $6,353 in the 2026 financial year. This benefit extends to your ongoing ownership as well. You save 10% on every litre of fuel, every set of tyres, and every scheduled service because these are also paid using GST-free funds. Over a three-year lease, these incremental savings on running costs can add thousands of dollars back into your household budget.
Because every individual’s tax situation is unique, using a novated lease calculator is the most efficient way to model your specific take-home pay impact. It allows you to see the real-world difference between a standard car loan and a tax-optimised lease, providing a clear picture of your potential annual savings.
Fringe Benefits Tax (FBT) and the ECM
The ATO views a car provided by an employer as a “fringe benefit,” which is normally subject to tax. However, most Australian drivers use the Employee Contribution Method (ECM) to offset this liability. By paying a small portion of the lease costs from your post-tax salary, you reduce the taxable value of the benefit to zero. This hybrid method ensures you get the maximum tax benefit on the bulk of your lease payments while staying completely compliant with ATO regulations. It is a pragmatic way to eliminate FBT without losing the advantages of salary packaging.
The 2026 EV Advantage: FBT-Free Leasing
For those considering the switch to electric, the savings are even more substantial in 2026. Eligible battery electric vehicles (BEVs) with a purchase price below the Luxury Car Tax threshold of $91,661 are currently FBT-exempt. This means you don’t need to use the ECM; the entire lease and all running costs can be paid from your pre-tax salary. This creates a massive boost to your take-home pay, making an EV novated lease australia one of the most effective financial tools available for modern professionals.
The Novated Lease Lifecycle: From Sourcing to Settlement
Understanding how does salary packaging a car work requires a clear view of the full lifecycle, from the showroom floor to the final settlement date. The journey begins with sourcing your vehicle. Unlike a private purchase where you negotiate as an individual, leasing providers often have access to “Fleet Discounting.” This allows them to secure vehicles at price points typically reserved for large corporations. When you combine these lower purchase prices with the GST savings mentioned earlier, the total amount you need to finance is significantly reduced before you even drive away.
Bundling Running Costs: Petrol, Rego, and Insurance
A core benefit of the leasing lifecycle is the consolidation of all vehicle expenses into one predictable monthly figure. Your provider creates a customised budget based on your estimated annual kilometres, covering everything from fuel to scheduled maintenance and tyres. Most leases include specialised fuel cards and automated registration renewals, which removes the administrative burden of ownership. Insurance is typically sourced at competitive group rates, ensuring you aren’t overpaying for coverage while keeping your budget protected from unexpected price hikes.
Every novated lease includes a “Residual Value,” which is a balloon payment required by the ATO at the end of the term. This figure is not arbitrary; it is a set percentage based on the length of your lease. For a three-year lease, the minimum residual is 46.88% of the vehicle’s initial cost. While some drivers feel anxious about this final payment, it is simply the portion of the car’s value that hasn’t been paid off through your pre-tax salary deductions. It effectively keeps your monthly payments lower throughout the term.
End-of-Lease Options: What Happens After 3-5 Years?
As you approach the end of your term, you generally have three strategic paths to choose from. The first is to pay the residual amount and own the car outright. If the vehicle’s market value is higher than the ATO residual, you can often sell it privately for a tax-free profit. The second option is to refinance the residual, allowing you to continue leasing the same car for another one or two years to further maximise your tax savings. The third and most popular path is to trade the car in, use the proceeds to settle the residual, and start a fresh lease on a new model.
To see how these lifecycle stages apply to your specific financial situation, you should compare novated lease quotes to find the most competitive interest rates and management fees in the 2026 market.
Choosing the Right Provider: Why Comparison is Key
While the legal framework of how does salary packaging a car work is standardised by the ATO, the financial efficiency of individual deals is not. Many drivers assume that all novated leases are identical because they use the same tax rules; however, this is a costly misconception. Interest rates, management fees, and the transparency of running cost budgets vary significantly between providers. If you don’t look beyond the headline monthly repayment, you might find that high hidden costs are quietly eroding the very tax savings you aimed to achieve.
The most effective way to protect your interests is through an independent novated lease comparison. By looking at the total cost of finance rather than just the paycheck deduction, you can identify which providers are offering genuine value and which are inflating their margins through undisclosed charges. Positioning yourself as an informed consumer allows you to leverage the competition between providers to secure a more favourable deal.
Red Flags to Watch Out For
When reviewing quotes, it’s vital to stay vigilant for certain industry practices that can diminish your financial optimisation. Look for these specific warning signs:
- High undisclosed fees: Some providers hide their management costs within the interest rate or bundled services.
- Inflated insurance premiums: Check if the provider is sourcing competitive rates or simply adding their own margin to a standard policy.
- Restrictive terms: Ensure the lease is portable and doesn’t include heavy penalties if you decide to change vehicles or employers before the term ends.
How to Get Started with Quotes
Finding the right fit for your 2026 financial goals requires a small amount of preparation. Before you begin, ensure you have your current gross salary and an honest estimate of your annual mileage ready. This data allows providers to build an accurate budget for your running costs and tax deductions. Once you have these details, you can use the Novated Lease Quotes platform to see the whole market at once. This independent service simplifies the process, allowing you to focus on the numbers that matter most to your take-home pay.
Ultimately, the goal is to understand exactly how does salary packaging a car work for your specific budget. By comparing multiple offers, you ensure that your vehicle remains a smart financial asset rather than just another monthly bill. With the right provider, your novated lease becomes a seamless, automated tool for building wealth while you drive.
Secure Your Financial Future on the Road
Understanding how does salary packaging a car work is the first step toward transforming a major household expense into a strategic financial asset. By leveraging the three-way agreement between you, your employer, and a financier, you can significantly reduce your taxable income while enjoying the convenience of a fully maintained vehicle. Whether you are capitalising on the 2026 FBT exemptions for electric vehicles or optimising a traditional petrol model, the savings on GST and income tax are substantial and immediate.
Success in salary packaging depends on transparency and comparison. You shouldn’t settle for the first quote provided by your employer’s preferred partner, as interest rates and management fees vary wildly across the market. Our independent platform offers a free, no-obligation service to help you Compare Multiple Novated Lease Quotes Now. Use our specialised 2026 calculator to model your take-home pay impacts and move forward with the confidence that you’re maximising every cent of your hard-earned salary. Start your journey toward smarter car ownership today.
Frequently Asked Questions
Is salary packaging a car worth it for someone on a middle income?
Yes, salary packaging is often highly effective for middle-income earners. By paying for your vehicle from your gross salary, you reduce the amount of income the ATO taxes. This can keep you in a lower tax bracket while you enjoy the GST savings on the purchase price and running costs. To understand exactly how does salary packaging a car work for your specific pay grade, you should use a calculator to model the impact on your fortnightly take-home pay.
Can I include a used car in a novated lease agreement?
You can certainly include a used car in a novated lease agreement. Most providers allow vehicles up to 10 or 12 years old at the end of the lease term. While you might not save the GST on the purchase price if buying from a private seller, you still benefit from paying for all running costs and lease repayments with pre-tax dollars. This makes packaging a reliable used vehicle a smart way to minimise depreciation costs.
What happens to my novated lease if I change jobs or get made redundant?
If you change jobs, your novated lease is portable and can move with you to your new employer. You simply need to ensure your new workplace offers salary packaging. If you are made redundant, the lease typically reverts to a standard finance arrangement where you pay from your bank account until you secure new employment. It is a flexible structure that prioritises your ownership of the vehicle regardless of your current employer.
Is there a limit on how many kilometres I have to drive each year?
There is no longer a minimum or maximum limit on the kilometres you must drive each year. The ATO removed the old distance-based tiers years ago, meaning you receive the same tax benefits whether you drive 5,000 or 50,000 kilometres. Your leasing provider will simply help you set a realistic budget for fuel and maintenance based on your expected usage to ensure your payroll deductions accurately cover your actual on-road expenses.
Do I have to use the leasing company my employer recommends?
While many employers have a preferred provider for payroll administration, you are often entitled to compare quotes from other sources to ensure you get a competitive interest rate. Understanding how does salary packaging a car work across different providers is essential because management fees and finance costs vary significantly. Even if you must use a specific administrator, you can often negotiate the underlying finance deal by presenting a more competitive independent quote.
What exactly is a residual value or balloon payment?
The residual value, or balloon payment, is a final lump sum required by the ATO at the end of your lease term. It represents the remaining value of the car that hasn’t been paid off through your salary deductions. For example, a three-year lease has a minimum residual of 46.88%. At the end of the term, you can pay this to own the car, refinance it to continue leasing, or trade the vehicle in to start a new lease.
Can I salary sacrifice a car for my spouse or partner?
You can salary sacrifice a car that is primarily driven by your spouse or partner. The lease agreement must remain in your name and be processed through your employer’s payroll, but the ATO does not restrict who drives the vehicle for personal use. This is a popular strategy for households to reduce their overall tax debt by packaging multiple vehicles through the highest-earning partner’s salary to maximise the savings available within higher tax brackets.
Are fuel and maintenance costs really tax-free?
Fuel and maintenance costs are effectively tax-free because they are paid using your pre-tax income. This means you aren’t paying your highest marginal tax rate on the money used for petrol, servicing, or tyres. Additionally, your provider claims back the 10% GST on these expenses and passes that saving directly to you. It is one of the most efficient ways to lower the total cost of car ownership while keeping your vehicle in peak condition.


