What if the most expensive way to buy your next electric vehicle is actually with your own savings or a standard car loan? Many Australians feel understandably cautious about salary packaging, especially with the 2026 FBT exemption changes and the fear of hidden fees buried in the fine print. You’ve likely heard that an EV can save you thousands, but without a clear picture of your actual take-home pay, it is hard to make a confident financial decision.
This guide demonstrates how to use an ev novated lease calculator to accurately model your financial position and validate those projected tax savings. We promise to help you cut through the confusion surrounding the 2026 luxury car tax thresholds and the shifting eligibility rules for different vehicle types. We will provide a clear breakdown of the fortnightly impact on your salary, compare leasing directly against traditional finance, and show you how to source competitive quotes from multiple providers. This ensures you are not overpaying for your transition to electric driving while the most generous incentives are still available.
Key Takeaways
- Understand how the tapering FBT exemption and the Electric Car Discount impact your long-term savings before the 2026 regulatory shifts.
- Utilise an ev novated lease calculator to accurately model your specific salary and driving habits while accounting for the significant GST credit.
- Discover why the total cost of ownership over five years often makes a lease more affordable than a standard car loan.
- Learn to identify “padded” running costs and hidden fees in leasing quotes to protect your fortnightly take-home pay.
- Realise the maximum financial benefit by comparing multiple competitive quotes from specialist providers rather than settling for a single estimate.
Understanding the 2026 EV Novated Lease Landscape
2026 represents a pivotal window for Australian drivers. It is the final full year to secure a lease under the current, most generous version of the Federal Government’s Electric Car Discount before tapering begins in April 2027. To understand the fundamental mechanics of these three-way agreements between you, your employer, and a financier, it helps to first define What is a novated lease? At its core, this arrangement allows you to pay for a vehicle and its running costs using a combination of pre-tax and post-tax salary. An ev novated lease calculator bridges the gap between a vehicle’s recommended retail price and your actual fortnightly take-home pay, turning abstract tax laws into concrete financial data.
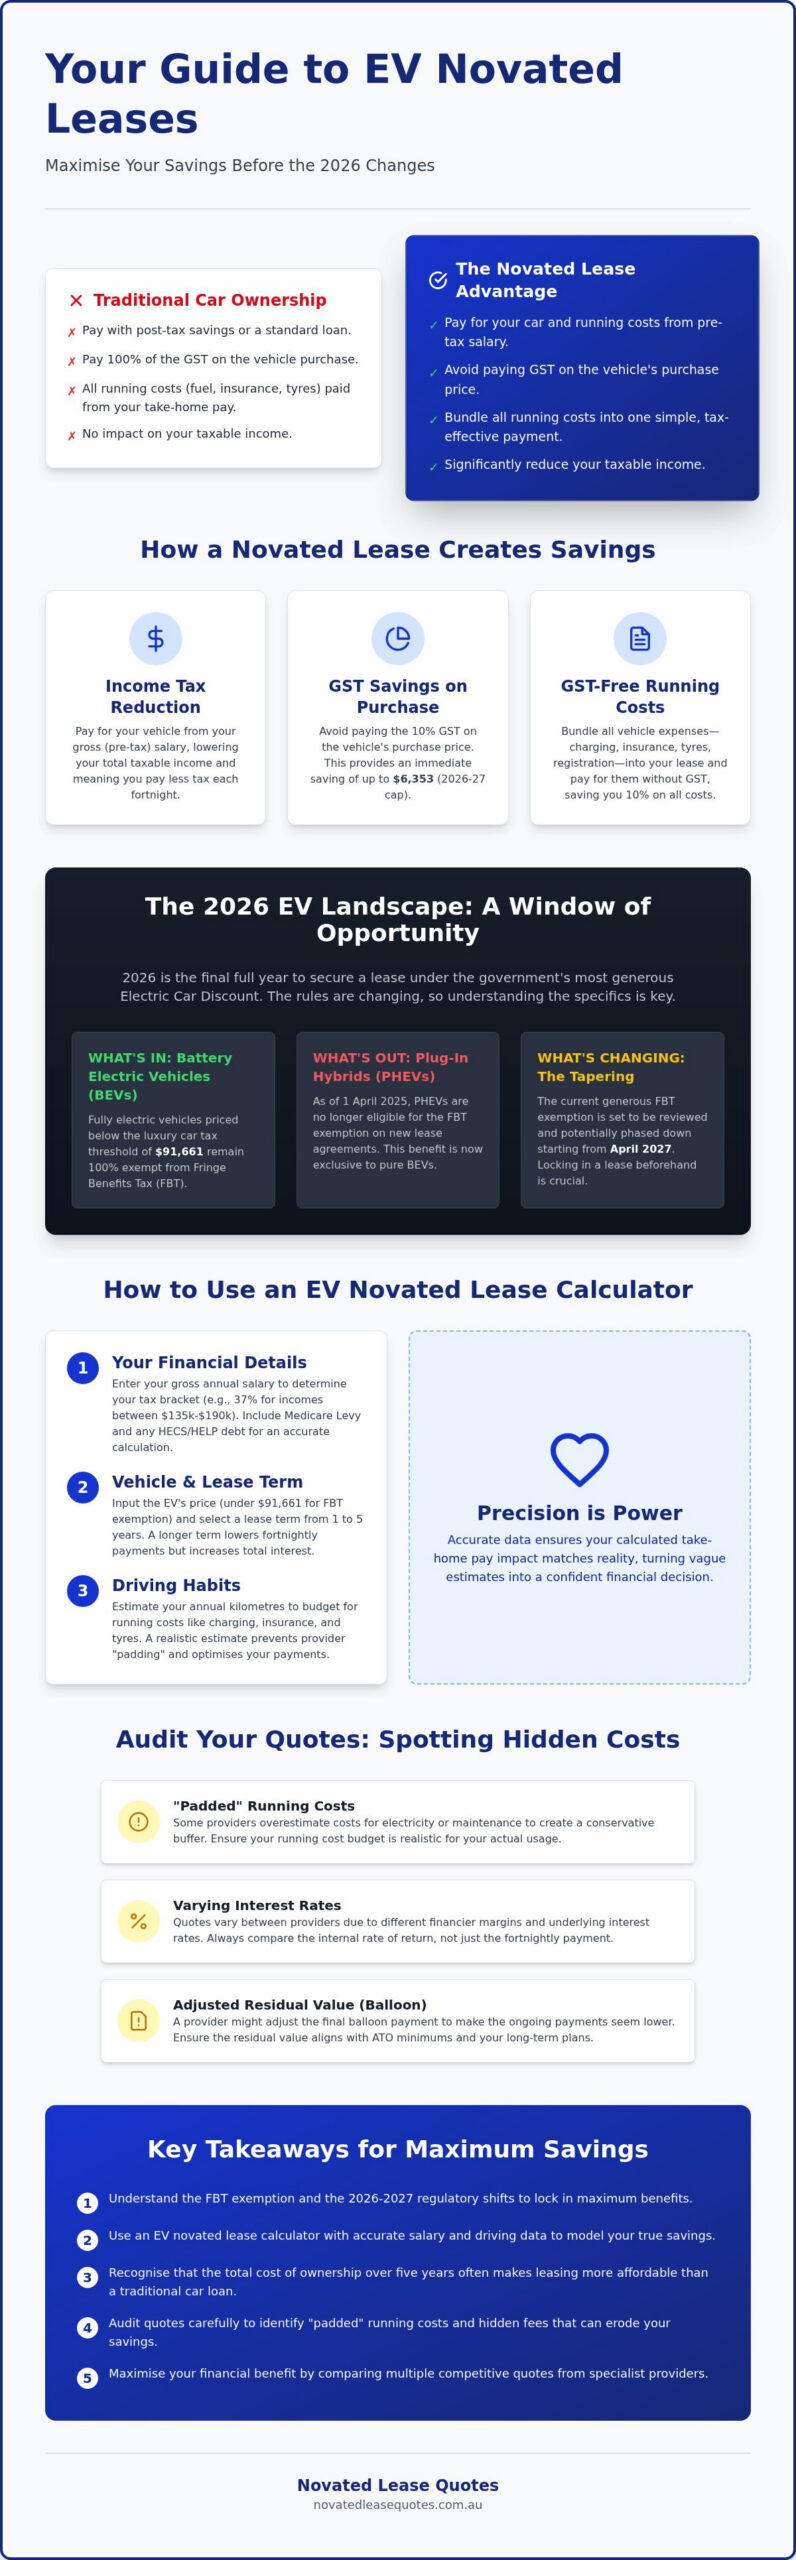
The savings framework rests on three primary pillars. First, the tax benefit allows you to reduce your taxable income by paying for the lease from your gross salary. Second, you avoid the 10% GST on the vehicle purchase price, capped at the 2026-27 maximum credit of $6,353. Third, all running costs, including charging, tyres, and insurance, are bundled into that same tax-effective payment structure. This creates a significant “buffer” that traditional car loans simply cannot match.
The FBT Exemption Advantage
The Fringe Benefits Tax (FBT) exemption is the engine room of EV salary packaging. By removing the 20% FBT typically applied to employer-provided vehicles, the government has made battery electric vehicles (BEVs) significantly more affordable than petrol or diesel equivalents. However, the regulatory context for 2026 is specific. While BEVs remain fully exempt, plug-in hybrids (PHEVs) were removed from the exemption list for new leases as of 1 April 2025. For the 2026 calendar year, the maximum benefit applies to pure electric models priced below the $91,661 luxury car tax threshold for fuel-efficient vehicles.
Why Estimates Vary Between Providers
Even when using an ev novated lease calculator, you’ll notice that quotes from different providers rarely align perfectly. These variations often stem from financier margins and the underlying interest rates. Some providers “pad” their running cost estimates, such as electricity or maintenance, to create a conservative buffer, while others might adjust the residual value (the balloon payment) to make monthly cash flow appear more attractive. It’s vital to look beyond the initial monthly figure and audit the internal rate of return to ensure the calculator’s projected savings actually materialise in your bank account.
How to Use an EV Novated Lease Calculator Accurately
To extract an accurate result from an ev novated lease calculator, you must look beyond the vehicle’s sticker price. Precision in your data entry ensures that the projected fortnightly take-home pay impact matches reality rather than being a vague estimate. Most users overlook the specific mechanics of the GST credit, which is a critical input. Because the leasing company is registered for GST, they can claim back the 10% GST on the car’s purchase price, up to the 2026-27 limit of $6,353. This effectively reduces your financed amount from day one, a benefit you won’t find with a standard car loan.
Your annual kilometres also dictate your running cost budget. While electric vehicles require less maintenance than internal combustion engines, you still need to account for tyres, insurance, and charging costs. Setting a realistic budget here prevents “padding” from the provider, ensuring your salary sacrifice amounts are optimised. Higher income earners in the 37% or 45% tax brackets will see a more pronounced benefit, as every dollar sacrificed from pre-tax income represents a larger tax saving.
Inputting Your Financial Details
Your taxable income is the most significant factor in the calculation. For the 2026-27 financial year, someone earning between $135,001 and $190,000 sits in the 37% tax bracket. An accurate calculator will factor in the Medicare Levy and any HECS/HELP debt, as these obligations change based on your adjusted taxable income. If your employer uses a specific salary packaging provider, there may also be small administration fees to include for absolute precision. Once you have these figures ready, you can use our ev novated lease calculator to see the numbers in action.
Selecting the Right Lease Term
Lease durations typically range from one to five years. A shorter term results in higher fortnightly payments but lowers the total interest paid over the life of the agreement. Conversely, a five-year term reduces the immediate impact on your take-home pay but results in a larger residual value. The ATO sets minimum residual percentages, such as 28.13% for a five-year term, which you must pay at the end of the lease to own the vehicle outright. Balancing these factors is essential for long-term financial health.
Comparing a Novated Lease vs. Car Loan for EVs
A standard car loan is often the default choice for many buyers, but it is rarely the most cost-effective path for an electric vehicle. The “effective interest rate” is a common point of confusion. While a bank might offer a nominal interest rate that looks lower on paper, it does not account for the tax-free nature of lease payments. When you use an ev novated lease calculator, you quickly see that paying for a car with post-tax income is significantly more expensive. For instance, a person on a $100,000 salary packaging a $50,000 EV could save between $8,000 and $12,000 annually compared to a personal loan. This is because the lease payment is deducted before your income tax is calculated, effectively lowering the cost of the finance itself.
Regarding borrowing capacity, lenders view novated leases differently than personal loans. Because the payment is a salary deduction, it reduces your reportable gross income. While this might slightly lower the maximum amount you can borrow for a mortgage, it also eliminates the need for separate car loan repayments and running cost buffers in your living expenses. It’s a trade-off that requires careful modelling based on your long-term financial goals, particularly if you plan to enter the property market soon.
The Pre-Tax vs. Post-Tax Difference
The primary advantage of a lease is the shift from post-tax to pre-tax spending. When you take out a bank loan, you pay the financier with money that has already been taxed at your marginal rate. With a novated lease, your salary is “sacrificed” before the ATO takes its cut. This means you are essentially buying the vehicle and its running costs with “gross” dollars. This advantage extends to every aspect of the vehicle’s life. Tyres, servicing, and even your home charging costs are paid using pre-tax funds. Because the leasing provider claims the GST back, you avoid that 10% cost entirely on your maintenance and charging supplies.
Residual Values and the Balloon Payment
Every novated lease includes a residual value, often called a balloon payment, which is the amount required to own the car at the end of the term. For EVs, residual values are becoming more predictable as the secondary market matures. In 2026, you have several options when the lease ends: you can pay the residual to keep the car, sell the vehicle and use any profit (which is tax-free) to start a new lease, or simply refinance the balloon amount. Because EV technology evolves rapidly, a shorter lease term can be a smart way to stay in the latest model while the FBT exemption remains active.
Audit Your Quotes: Spotting Hidden Costs
A calculator provides the theoretical framework for your savings, but a formal quote represents the reality. Discrepancies between the two are where hidden costs often reside. A common industry practice involves “padding” running cost estimates. While having a small buffer for charging or maintenance is sensible, excessively high estimates unnecessarily reduce your fortnightly take-home pay. If a provider’s estimate for electricity or tyres is significantly higher than what you found using an ev novated lease calculator, you are effectively losing access to that cash until the end of the lease term.
Transparency regarding the interest rate, often expressed as the Internal Rate of Return (IRR), is another critical audit point. Many providers omit the nominal interest rate or hide margins within undisclosed procurement commissions. By using your ev novated lease calculator results as a benchmark, you can challenge these figures. It is essential to request multiple novated lease quotes from different specialists to ensure you aren’t paying a premium for a standard service.
The Red Flags in a Provider Quote
Bundled insurance is a frequent culprit for inflated costs. Providers often include comprehensive policies that are more expensive than those you could source independently. Always compare the quote’s insurance premium against your existing insurer. Another red flag is an inflexible residual value. The ATO sets specific minimums, such as 28.13% for a five-year term or 46.88% for a three-year term. If a provider deviates significantly from these without a clear explanation, it can skew your monthly cash flow and lead to a financial surprise when the lease ends. Vague “administration charges” should also be itemised and transparent.
Using the Calculator as a Benchmark
Your initial calculation serves as your financial baseline. When a quote arrives, match the projected net take-home pay against your original model. If there is a meaningful difference, investigate the GST treatment. The $6,353 GST credit on the purchase price must be correctly applied to reduce the financed amount. Most importantly, for any eligible battery electric vehicle in 2026, the quote should explicitly show a $0 Fringe Benefits Tax liability. To ensure you are getting the best deal possible, you can compare competitive quotes through our national network of specialists.
Next Steps: From Calculation to Comparison
Establishing your financial baseline with an ev novated lease calculator is a vital first step, but it is only the beginning of your journey. A calculator provides a theoretical model based on current tax laws and average market rates. To turn that model into a reality, you need a firm contract from a provider who can deliver on those projected savings. Relying on a single quote is a common mistake that often leads to missed opportunities. Different leasing companies have varying relationships with car dealerships and financiers, meaning the procurement price and interest rate can differ by thousands of dollars over the life of the agreement.
Leasing specialists often have access to fleet pricing that is unavailable to the general public. A comparison service allows you to audit these procurement claims against the market, ensuring the vehicle price entered into your ev novated lease calculator remains accurate during the actual purchase. This ensures you aren’t paying a retail premium on a vehicle that should be discounted for a professional lease. Document preparation is the final hurdle. Most providers require your two most recent payslips, proof of residency, and a copy of your driver’s licence to finalise the credit approval.
Securing Multiple Quotes
Our platform simplifies this complexity by connecting you with a network of leading Australian providers. By using a centralised novated lease comparison, you save hours of manual research and data entry. This competitive environment works in your favour. When providers know they are being compared side-by-side, they are more likely to offer their most aggressive rates and transparent fee structures. You can then leverage these competing quotes against each other to lower the interest rate and reduce the overall cost of ownership.
Finalising Your Salary Packaging Agreement
Once you have selected a provider, the focus shifts to your workplace. You will need to coordinate with your HR or payroll department to ensure they are ready to facilitate the salary deductions. This involves confirming the EV novated lease australia specific terms, particularly the FBT-exempt status of your chosen vehicle. Having your organisational details ready will expedite the final application and ensure a seamless transition to your new electric vehicle.
Before signing your deed of novation, review this final checklist:
- Verify the residual value matches ATO minimums for your specific lease term.
- Check that the GST credit has been applied to reduce the financed amount.
- Ensure all running cost budgets align with the figures from your novated lease calculator.
- Confirm your employer’s payroll department is ready for the first deduction.
Secure Your 2026 Tax Advantages Today
Transitioning to an electric vehicle is a significant financial step that requires more than a surface-level estimate. You’ve seen how the 2026 landscape demands precision, from correctly accounting for GST credits to understanding the specific eligibility of battery electric models. An ev novated lease calculator serves as your essential benchmark, allowing you to audit formal quotes and protect your fortnightly take-home pay from hidden management fees or inflated running cost buffers. By modelling your specific salary bracket and driving habits, you can move from uncertainty to a clear, data-driven decision.
The difference between a standard car loan and a professionally structured salary packaging deal can represent thousands of dollars in annual savings. To ensure you’re realising the full potential of the Electric Car Discount, it’s vital to compare the market through a specialist lens. Get Competitive EV Novated Lease Quotes Now to access our 100% independent comparison service. We connect you with multiple Australian providers and offer specialist EV tax advice to ensure your deal is optimised for your financial goals. Take control of your electric transition today and drive a more efficient future.
Frequently Asked Questions
Is the EV FBT exemption still available in 2026?
Yes, the full Fringe Benefits Tax exemption remains active for battery electric vehicles (BEVs) throughout 2026. This incentive applies to vehicles priced below the luxury car tax threshold of $91,661 for the 2026-27 financial year. It’s important to remember that plug-in hybrids (PHEVs) were removed from this exemption on 1 April 2025. By using an ev novated lease calculator, you can confirm your specific vehicle’s eligibility and model the significant tax savings before the scheme begins to taper in April 2027.
Can I include a home charger in my EV novated lease calculator?
You can typically include the cost of a home charging station if it is bundled as an accessory with the vehicle purchase. This allows you to pay for the hardware and installation using pre-tax salary, effectively reducing the net cost by your marginal tax rate. When inputting figures into an ev novated lease calculator, ensure the total vehicle price, including the charger, remains under the $91,661 fuel-efficient luxury car tax threshold to maintain your FBT-exempt status.
What happens if I exceed the Luxury Car Tax (LCT) threshold?
Exceeding the fuel-efficient LCT threshold, which is $91,661 for the 2026-27 period, results in the loss of the FBT exemption. This change makes the lease significantly more expensive as you would then be liable for the standard 20% fringe benefits tax. Additionally, you will incur the luxury car tax itself on the portion of the price above the threshold. Always verify the final “drive-away” price against current ATO limits to ensure your packaging remains tax-effective.
Does a novated lease affect my superannuation contributions?
A novated lease generally does not reduce your superannuation entitlements. In Australia, employers are required to pay the Superannuation Guarantee based on your gross “ordinary time earnings” before any salary sacrifice deductions are made. However, it is always professional practice to confirm this with your payroll department. Some employers may have specific policies regarding how salary packaging interacts with reportable fringe benefits, which can occasionally impact other government benefits or the Medicare Levy Surcharge.
Can I package a second-hand electric vehicle?
You can package a used electric vehicle provided it meets the financier’s age and condition criteria. To qualify for the FBT exemption, the vehicle must have been first held and used on or after 1 July 2022. Crucially, the luxury car tax must never have been payable on the vehicle when it was sold as new. If a car was over the LCT threshold originally, it remains ineligible for the exemption even if the second-hand price falls below it.
What is the minimum residual value for a 3-year EV lease?
The Australian Taxation Office (ATO) sets the minimum residual value for a three-year lease at 46.88% of the original purchase price. This “balloon” payment is the amount you must pay at the end of the term to own the vehicle outright. While you can choose to set a higher residual value to lower your fortnightly payments, you cannot set it lower than this prescribed percentage. This ensures the lease remains a legitimate commercial arrangement in the eyes of the tax office.
How does charging at home work with a novated lease budget?
Charging at home is a claimable running cost that can be paid from your pre-tax salary. The ATO provides a shortcut method for calculating these costs, currently set at 4.2 cents per kilometre, which simplifies the process of tracking electricity usage. Alternatively, you can track actual costs if you have a dedicated smart charger. Including these estimates in your budget ensures your take-home pay reflects the true cost of operating your electric vehicle compared to a petrol equivalent.
What happens to the lease if I change employers?
Novated leases are designed to be portable, meaning you can take the vehicle and the finance agreement to a new job. Your new employer must agree to sign a new deed of novation to continue the salary deductions. If there is a gap between jobs, or if a new employer refuses to participate, the lease becomes a “non-novated” agreement. In this scenario, you would be responsible for making the full lease payments from your post-tax bank account until a new novation is established.


