
Your novated lease doesn’t vanish when your employment ends; it simply changes its legal shape. Losing your job shouldn’t mean losing your car, but it does mean your lease transforms overnight from a tax-efficient benefit into a direct personal obligation. It’s natural to feel a sense of urgency about what happens if I lose my job with a novated lease, especially when you’re already managing the stress of a career transition. You’ve likely grown used to the convenience of automated pre-tax payments, so the prospect of a sudden spike in costs or complex paperwork is understandably daunting.
This guide provides the professional clarity you need to maintain control over your finances and your vehicle. We’ll show you exactly how the de-novation process works, from the moment your employer stops their contributions to the day you re-novate with a new company. You’ll learn how to manage post-tax payment obligations, understand the 2026 GST implications for private leaseholders, and explore strategies to either keep your car or exit the arrangement affordably. We’ve mapped out the transition steps so you can focus on your next career move with confidence.
Key Takeaways
- Understand the de-novation process and how the tripartite agreement transitions into a personal financial obligation within days of your employment ending.
- Gain a clear strategy for what happens if I lose my job with a novated lease, focusing on the transition from salary packaging to personal finance management.
- Identify the hidden costs of private lease maintenance, such as the 10% spike in running expenses once you can no longer claim GST credits on fuel and servicing.
- Explore proactive safeguards like redundancy cover and Lease Protection Insurance that can manage your monthly obligations while you transition between roles.
- Utilise a specialised novated lease calculator to compare competitive quotes and find providers that offer the most flexible terms for career changes.
The De-novation Process: What Happens When Employment Ends?
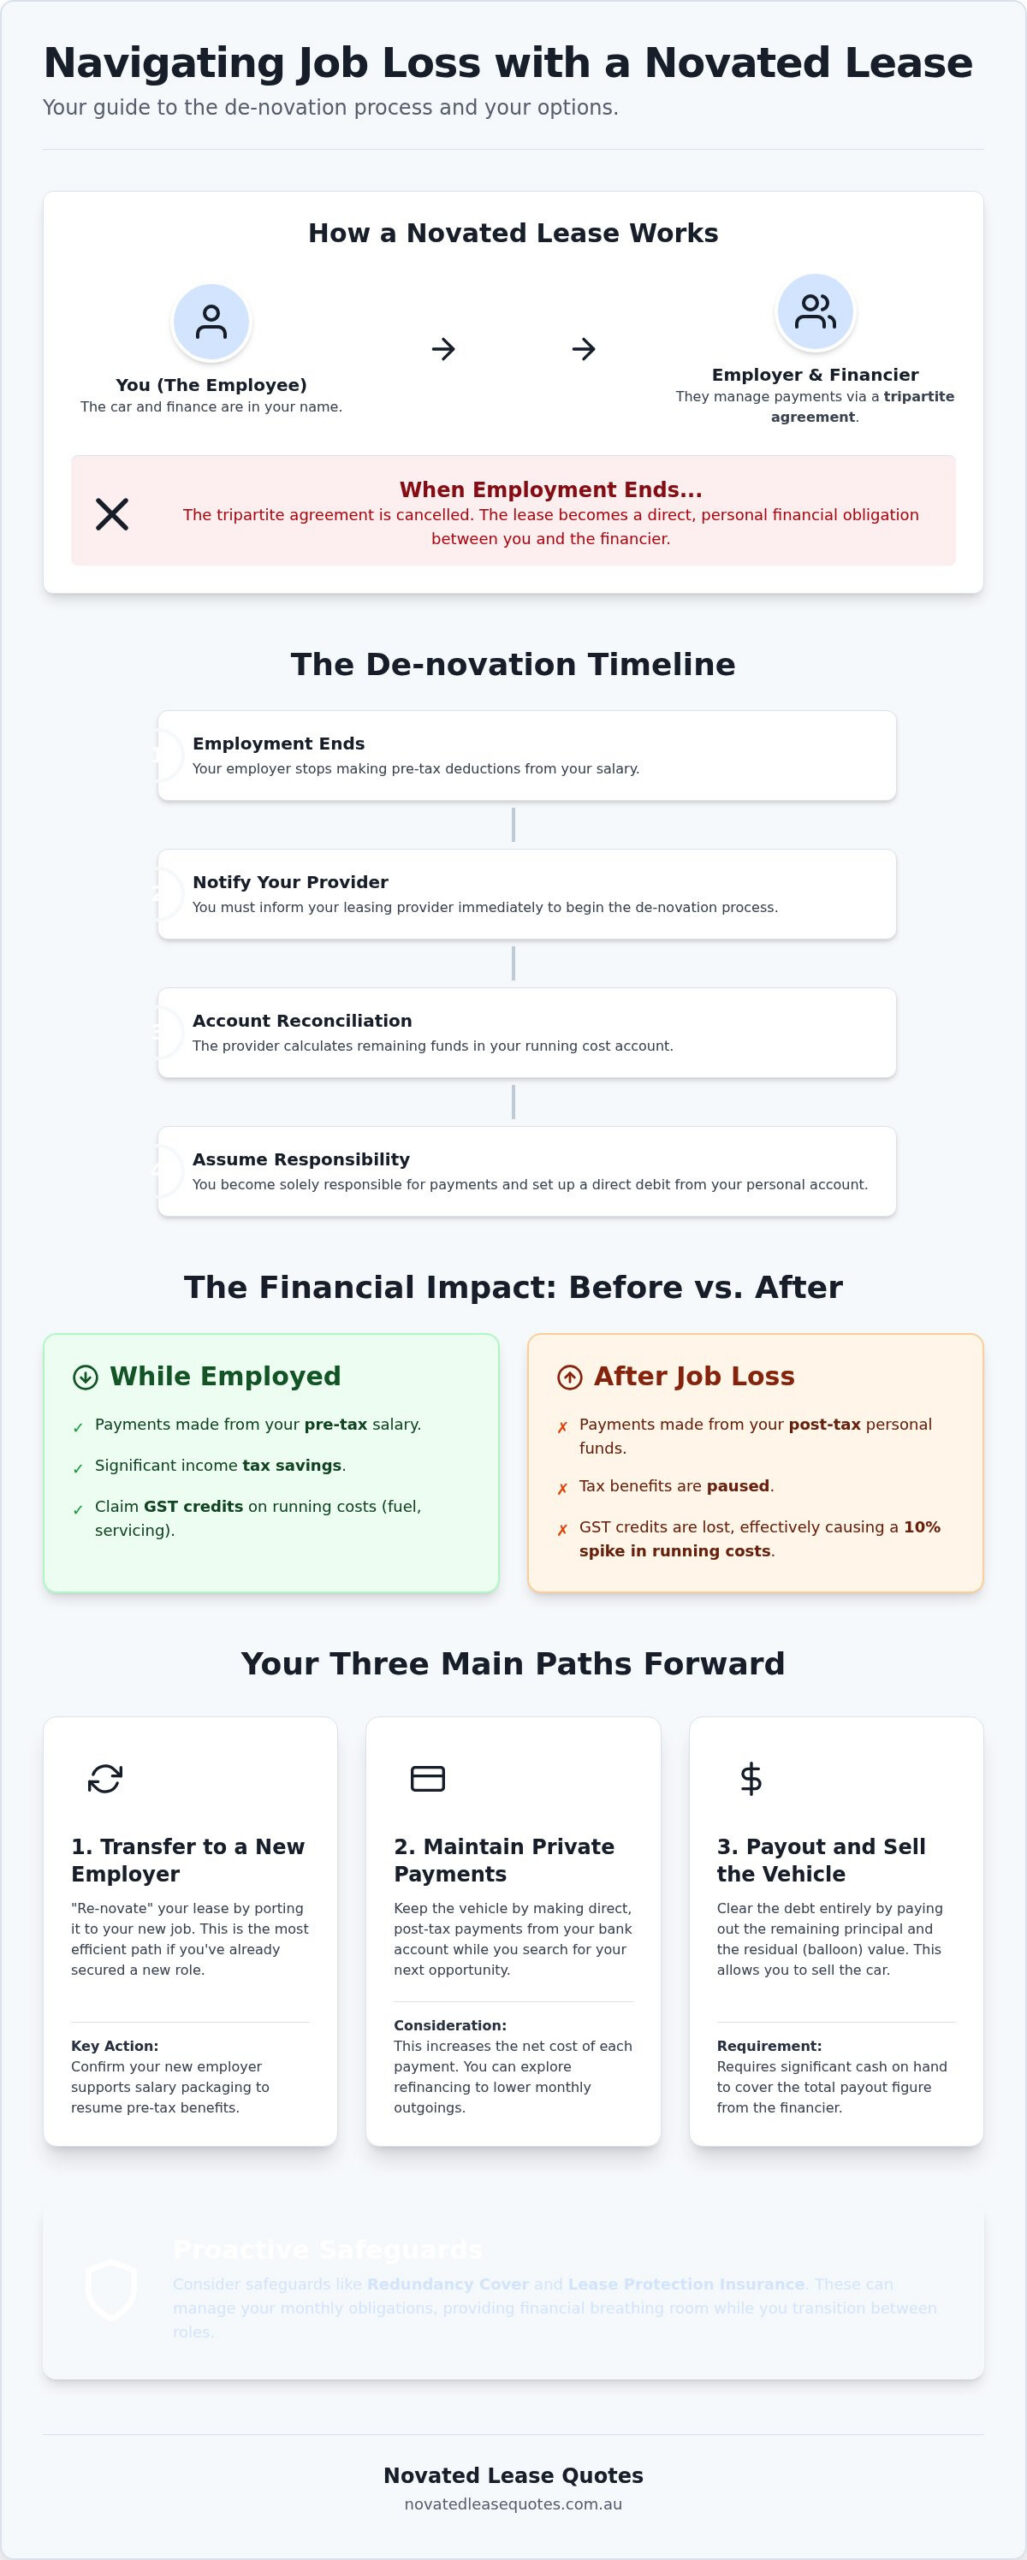
De-novation is the technical term for the process of removing your employer from your vehicle’s salary packaging arrangement. To understand the mechanics of this shift, it’s helpful to revisit What is a Novated Lease? at its core. Essentially, it’s a three-way, or tripartite, agreement between you, your employer, and the finance company. When your employment ends, the “novation” component of the contract is cancelled. This leaves you with a direct, bipartite agreement between yourself and the financier.
Knowing exactly what happens if I lose my job with a novated lease is vital for maintaining your credit rating and keeping your vehicle. Within the first 48 hours of leaving your role, the de-novation process begins. Your employer will stop making pre-tax deductions from your salary and will notify the leasing provider of your final day of work. From this point, you become solely responsible for the lease payments and all associated running costs using your own funds.
Step-by-Step De-novation Timeline
The transition moves quickly to ensure the financier is not left without payment. First, you must notify your leasing provider immediately to ensure they don’t attempt to draw funds from an employer who is no longer paying you. Following this, the provider will conduct an account reconciliation. This involves calculating any remaining funds in your running cost account, such as money set aside for fuel, tyres, or insurance. Finally, you’ll need to set up a direct debit from your personal bank account. This ensures the finance company receives their payments on time, preventing any default notices while you’re between jobs.
The Finance Agreement vs. The Novation Agreement
A common fear among employees is that the car belongs to the company. In reality, the finance agreement, which is the actual car loan, has always been in your name. The novation agreement was simply the legal bridge that allowed your employer to take over the payment obligations using your pre-tax income. When you lose your job, that bridge is removed, but the car and the loan stay with you. While the tax benefits pause, your ownership of the asset remains secure. You aren’t losing the vehicle; you’re simply changing how it’s funded until you secure your next role.
Your Three Main Paths: Transfer, Continue, or Payout
Deciding your next move depends on your immediate financial liquidity and how quickly you expect to re-enter the workforce. Once the de-novation process is triggered, you aren’t forced into a single solution. Instead, you have three distinct routes to manage the transition and protect your credit profile. Each path has different implications for your cash flow and tax position.
Transferring to a New Employer
If you’ve already secured a new role or are deep in the interview process, the most efficient path is “re-novation.” This process allows you to port your existing lease to a new employer. Your new payroll department simply signs a new novation agreement, and the pre-tax deductions resume as they did before. It’s essential to confirm that your new workplace supports salary packaging before you sign an employment contract. You should use a novated lease calculator to model how your new salary and tax bracket will affect your take-home pay. Since tax brackets are changing in 2026, recalculating your savings ensures the lease remains a smart financial move in your new role.
Maintaining Private Payments
For those currently job hunting, you can choose to keep the vehicle by making payments directly from your bank account. While this preserves your access to transport, you must recognise the shift in cash flow. You’ll be paying with 100% post-tax income, which effectively increases the “net” cost of each instalment because you lose the benefit of the salary sacrifice. If the monthly burden is too high, some financiers allow you to refinance the remaining balance. This can involve extending the lease term to lower the immediate monthly cash drain. Understanding what happens if I lose my job with a novated lease helps you prepare for these temporary out-of-pocket expenses while you search for your next opportunity.
Paying Out and Selling the Vehicle
If you prefer to clear the debt entirely, you can request a payout figure from your financier. This figure includes the remaining principal and the residual value, often called the “balloon” payment. The residual value is a pre-determined amount set at the start of the lease to satisfy ATO requirements. Selling the car privately can often cover this debt, depending on the vehicle’s market value. However, if the car’s value is lower than the payout figure, you’ll need to cover the “gap” with your savings. If you are considering a new arrangement in the future, comparing novated lease quotes can help you find terms that offer greater flexibility for potential career changes.
Calculating the Financial Impact: GST, Tax, and FBT
The financial transition following a job loss is often more significant than just the loss of a salary. When you move from a salary-packaged arrangement to a private one, the “hidden” subsidies that made the lease affordable disappear. Understanding what happens if I lose my job with a novated lease requires a forensic look at your cash flow. You’re moving from a system where your car was funded by gross income to one where every cent comes from your net, after-tax savings. This shift can increase your effective monthly vehicle costs by 30% to 45%, depending on your 2026 tax bracket.
Fringe Benefits Tax (FBT) also requires careful management during a partial year of employment. For the FBT year ending 31 March 2027, the statutory rate remains at 47%. If you lose your job mid-year, your employer will need to reconcile the FBT owed up to your final day. If you’ve been using the Employee Contribution Method (ECM) to reduce FBT to zero, you must ensure your final pay reflects the correct proportional contribution. Additionally, if you receive a redundancy payment, this lump sum could push you into a higher tax bracket for the financial year, which ironically increases the “value” of the tax deductions you received while you were still employed.
The GST Trap for Private Leases
One of the most immediate shocks to your budget is the loss of GST credits. Under a novated lease, your employer claims the GST on your fuel, servicing, and insurance, passing that 10% saving directly to you. Once the lease is de-novated, you’re viewed as a private individual by the ATO and can no longer access these credits. De-novated lessees lose the ability to claim GST credits on all vehicle expenses, effectively increasing the cost of fuel, servicing, and tyres by 10% overnight. This makes every trip to the petrol station or charging bay more expensive than it was during your employment.
Managing the Residual Value
The residual value, or balloon payment, represents the single largest financial risk if your employment ends unexpectedly. This figure is a non-negotiable amount that must be paid to the financier at the end of the lease term to take full ownership of the vehicle. If you’re currently between roles, saving for this lump sum can be difficult. It’s vital to review your original novated lease comparison to see if your provider offers flexible end-of-term options, such as refinancing the residual amount into a new personal loan. This can buy you more time to find a new role without the immediate pressure of a five-figure payout.
Proactive Protection: Lease Insurance and Redundancy Cover
Securing a novated lease is a strategic financial decision, but smart planning involves preparing for the unexpected. While earlier sections detailed the mechanics of de-novation, proactive protection through Lease Protection Insurance (LPI) can prevent the financial strain of job loss from ever reaching your bank account. LPI is a specialised insurance product designed to cover your lease obligations if you face involuntary unemployment. Instead of worrying about what happens if I lose my job with a novated lease, you can rely on the insurer to manage the monthly instalments on your behalf.
The cost of this cover is typically bundled into your monthly lease payment, making it a tax-effective addition. For many professionals, the premium is a small price to pay for the assurance that their primary mode of transport isn’t at risk during a career transition. When you are comparing options, look for policies that offer a hand-back feature. This allows you to return the car to the financier and have the remaining debt cleared if you are unable to find work within a certain timeframe. Most insurers require a waiting period before benefits begin, so it is vital to understand these terms before a crisis occurs.
Types of Lease Protection
Involuntary redundancy cover is the most common form of protection, usually providing between three and six months of lease payments. This gives you a critical window to secure a new role without draining your emergency savings. Some policies also include a hand-back option; the insurer settles the outstanding lease balance if you remain unemployed beyond the initial payment period. Eligibility typically requires you to have been in permanent, full-time employment for a minimum period, often six months, before a claim can be made. Casual or fixed-term contract workers should check their specific policy wording, as they may face different eligibility criteria.
Reviewing Your Current Policy
You should examine your original novation agreement or insurance certificate to see if this cover was included at the start. Many drivers opt-in during the initial setup without fully realising the extent of the benefits. Redundancy cover provides a financial buffer by meeting your lease repayments for a specified period, ensuring your vehicle remains secure while you focus on re-employment. If you find your current lease lacks this protection, you can often add it or negotiate hardship variations directly with your financier. To ensure you have the most robust protection for your next vehicle, you should compare novated lease quotes that specifically include comprehensive redundancy safeguards.
Finding Your Next Vehicle Solution with Professional Quotes
While it’s impossible to predict every career turn, understanding exactly what happens if I lose my job with a novated lease allows you to structure your next agreement with resilience in mind. The goal of salary packaging is to optimise your wealth, not create a financial trap. By selecting a lease with flexible terms and a provider that offers robust support, you can ensure your vehicle remains an asset rather than a liability during times of professional change. Taking control of this journey today means looking beyond the monthly repayment and examining the underlying contract for long-term stability.
The Value of Expert Comparison
Not all leasing providers handle employment transitions with the same level of transparency. Some companies charge significant de-novation fees to process the paperwork when you leave a role, while others facilitate a “re-novation” to a new employer with minimal administrative costs. When you use a comparison service, you can specifically look for financiers that offer superior hardship programmes. These programmes can be a lifeline if you are between jobs, offering temporary payment pauses or term extensions that a standard car loan would rarely provide. Our platform helps you identify these resilient structures, ensuring you aren’t just getting a low rate, but a partner that understands the Australian job market’s fluidity.
Planning for the Future
In the 2026 financial landscape, EV novated leases have become a primary tool for maximising savings due to their FBT-free status. This tax exemption makes the “real” cost of the vehicle much lower, which can be a significant advantage if you ever need to transition to private payments. Because the FBT liability is removed, the gap between your pre-tax and post-tax instalments is often narrower than it would be for a traditional petrol vehicle.
To further protect yourself, we recommend building a small “buffer” within your running cost account. While it’s tempting to set your budget to the cent, allowing a slight surplus to accumulate can cover your fuel or charging costs for several weeks if your income is interrupted. Consulting with a specialist before you sign your next agreement ensures that your lease is tailored to your specific career trajectory and risk tolerance. If you’re ready to find a deal that balances high-end savings with professional flexibility, you should get a competitive novated lease quote today and secure your financial future on the road.
Securing Your Mobility Through Career Changes
Job loss is a significant career hurdle, but it doesn’t have to result in the loss of your vehicle. By understanding the de-novation process and the transition from pre-tax to post-tax payments, you can maintain control over your finances. You now have a clear roadmap of the paths available, whether that involves transferring your lease to a new employer or utilising redundancy cover to bridge the gap while you hunt for your next role. Preparation is the most effective tool for long-term stability.
Knowing exactly what happens if I lose my job with a novated lease allows you to select providers with flexible hardship terms and robust insurance options from the start. Our independent platform provides access to Australia’s leading leasing specialists to ensure your salary packaging remains resilient against market changes. We offer objective quote comparisons and expert advice to help you build a financial buffer that protects your lifestyle.
If you are ready to explore a more secure vehicle solution, Compare Novated Lease Quotes for Your Next Vehicle today. Access expert advice and independent comparisons to find a lease that works for your career, no matter where it takes you. You have the knowledge to stay mobile and financially optimised.
Frequently Asked Questions
Do I have to give the car back if I lose my job?
No, you don’t have to return the vehicle because the finance agreement is in your name, not your employer’s. While the tax benefits of salary packaging stop, you retain full ownership of the car. You simply transition to a bipartite agreement where you pay the financier directly using post-tax funds. This ensures your mobility remains uninterrupted while you search for your next professional opportunity or prepare to transfer the lease.
Can I transfer my novated lease to a new employer immediately?
Yes, you can transfer the lease as soon as you start your new role, provided the company offers salary packaging. This process, known as re-novation, involves the new employer signing a novation agreement to resume pre-tax deductions. It’s a seamless way to restore your tax benefits. Before signing your new employment contract, it’s wise to confirm their policy on novated leasing to ensure your vehicle transition is as efficient as possible.
What happens to the money in my running cost account after redundancy?
Your leasing provider will perform a final account reconciliation to determine the balance of your running cost account. If there’s a surplus from your previous pre-tax contributions, the funds are typically returned to your employer. The employer then pays this out to you as taxable income through your final payroll. It’s vital to check this reconciliation carefully to understand what happens if I lose my job with a novated lease regarding your accumulated funds.
Will I have to pay GST on my car payments if I am unemployed?
Yes, you’ll effectively pay GST on all vehicle-related expenses once the lease is de-novated. Under a salary package, your employer claims the GST credits and passes the savings to you. As a private individual, you’re no longer eligible for these credits, meaning fuel, servicing, and lease instalments will cost 10% more. This shift to post-tax spending is one of the most immediate financial impacts of moving to a private lease arrangement.
Is there a fee for de-novating a lease early?
Most leasing providers charge an administrative fee to process a de-novation. This fee covers the cost of reconciling your running cost account, notifying the financier, and updating the legal contracts from a tripartite to a bipartite agreement. While these fees vary between providers, they are generally standard across the industry. Reviewing your original agreement will help you identify any specific costs associated with ending the employer’s involvement in your lease.
Can I sell my car while it is still under a novated lease agreement?
You can sell the vehicle at any time, but you must settle the outstanding finance balance with the lender. This payout figure includes the remaining principal and the residual value, often called a balloon payment. If the sale price exceeds the payout figure, you keep the profit tax-free. However, if the car’s market value is lower than the debt, you’ll need to cover the shortfall from your own savings to clear the encumbrance.
What happens if I cannot afford the private payments after losing my job?
If private payments become a struggle, you should contact your financier immediately to discuss hardship variations. Many lenders offer temporary payment deferrals or term extensions to lower your monthly outgoings. If you previously opted for Lease Protection Insurance, you may be eligible to have your payments covered for several months. Proactive communication with your provider is the best way to protect your credit rating during an unexpected period of unemployment.
Does a novated lease affect my redundancy payout?
A novated lease doesn’t reduce your statutory redundancy entitlement, but it does affect your final take-home pay. Your employer will deduct any outstanding lease payments and FBT obligations from your final salary before it’s paid out. Additionally, any surplus funds returned from your running cost account will be added to your final payment and taxed accordingly. Understanding what happens if I lose my job with a novated lease ensures you can accurately forecast your final payout.


