A novated lease is a sophisticated financial strategy rather than a simple car loan, yet most drivers treat the application like a standard trip to the dealership. Skipping the preparation phase is the fastest way to leave thousands of dollars on the table through missed GST credits or overlooked FBT exemptions. Having a comprehensive novated lease checklist is essential to ensure you aren’t caught out by the shifting regulations of 2026, especially as the rules for electric vehicles and plug-in hybrids continue to evolve.
It’s understandable if you feel overwhelmed by technical jargon or the fear of hidden fees buried in the fine print. You want the significant tax benefits of salary packaging without the administrative headache of navigating your employer’s internal policies. This guide provides the clarity you need to move forward with total confidence. We will detail every required document, explain how to compare quotes effectively, and show you exactly how to maximise your take-home pay. From the initial calculation to the final signature, you’ll have a clear roadmap to securing the best possible deal on your next vehicle.
Key Takeaways
- Confirm your eligibility by verifying your employer’s salary packaging policy so you don’t waste time on an ineligible application.
- Streamline your application by using our novated lease checklist to organise essential documents like recent pay slips and your Australian drivers licence.
- Secure a competitive deal by learning to identify hidden procurement fees and comparing the effective interest rate across different providers.
- Maximise your 2026 tax savings by selecting electric vehicles that sit below the Luxury Car Tax threshold for a full FBT exemption.
- Navigate the final stages with confidence by understanding the transition from credit approval to signing the formal Novation Agreement.
Eligibility Audit: Can You Salary Sacrifice a Car?
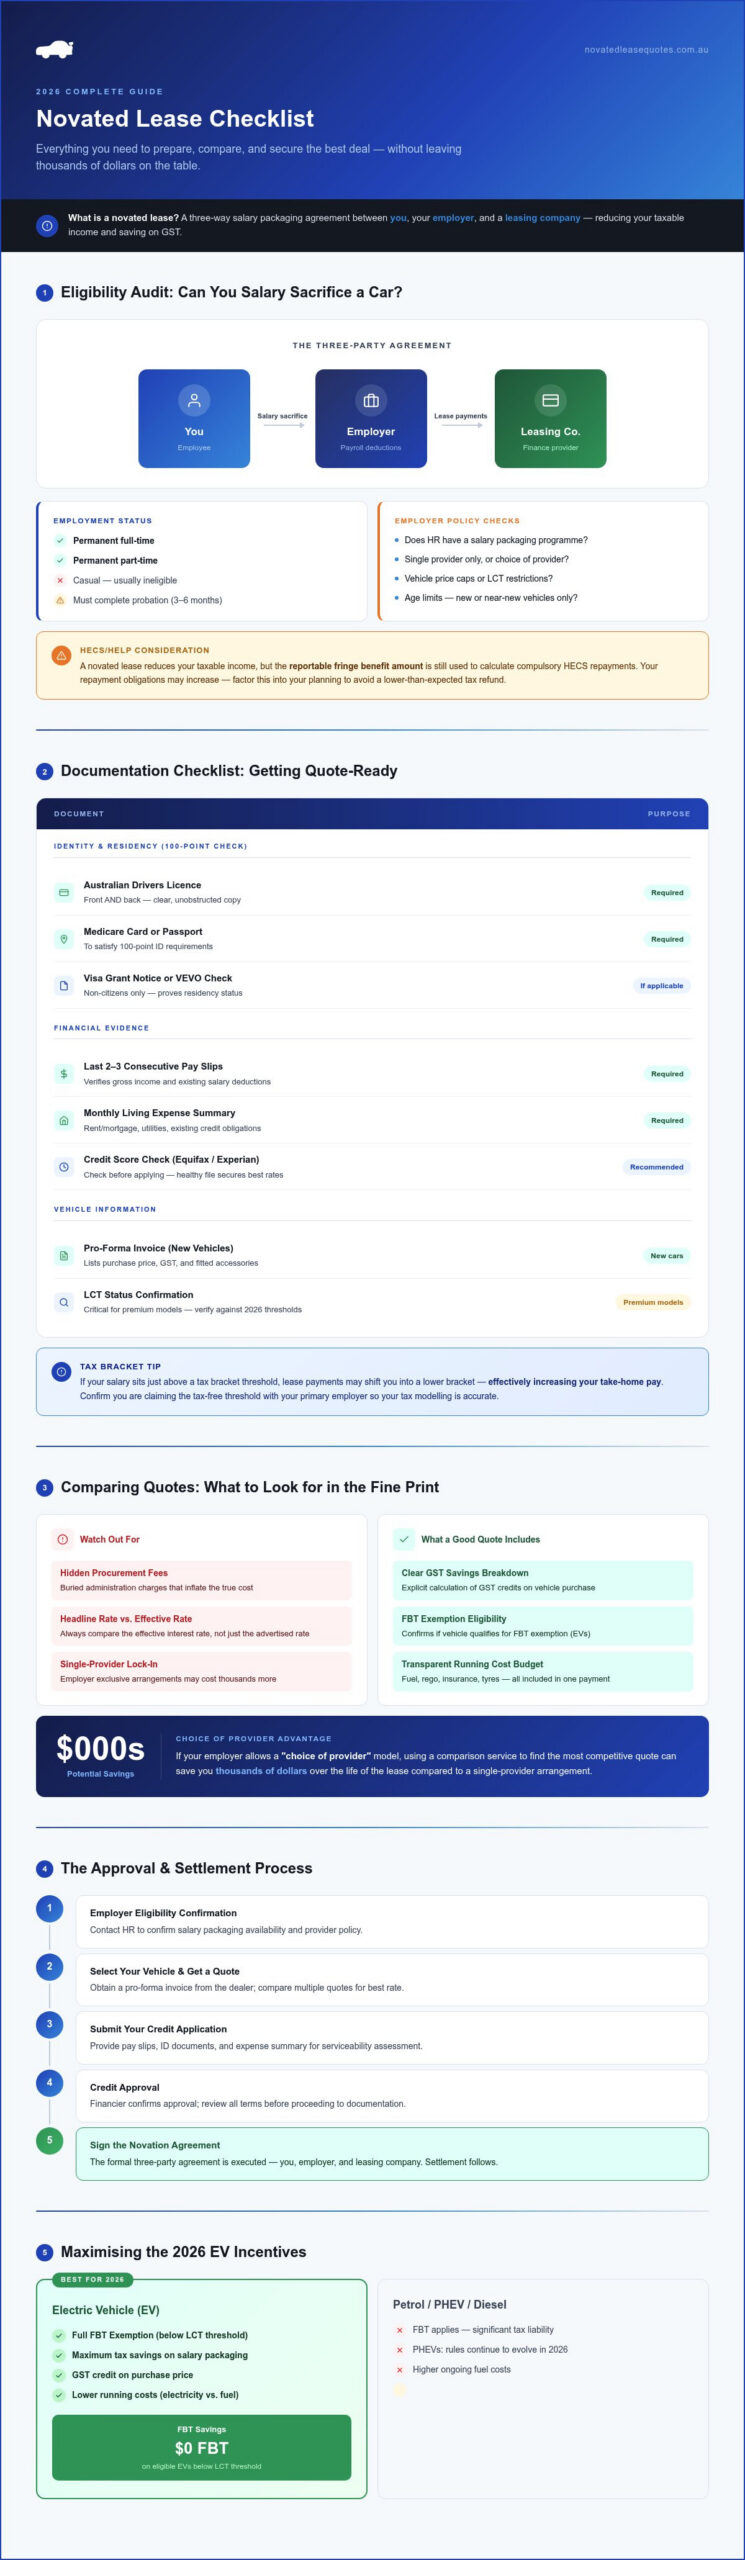
Before you tick off the first item on your novated lease checklist, you must confirm that the arrangement is actually available to you. Unlike a standard car loan where the relationship is strictly between you and a bank, a novated lease is a three-way agreement involving your employer. If your workplace doesn’t have the necessary payroll infrastructure or a policy in place, the process cannot begin. Most Australian employers are open to the idea because it costs them nothing to implement and provides a significant benefit to staff retention.
Your employment status is the next hurdle. Most financiers require you to be a permanent employee, either full-time or permanent part-time. Casual employees usually find it difficult to secure approval because the lease is tied to a steady salary sacrifice arrangement through payroll. Additionally, check your contract for your probation status. Most leasing companies require you to have completed your initial three or six-month probation period before they’ll approve the credit facility. If you’ve just started a new role, you might need to wait until that period is finalised.
Employer Participation and Policy Check
Start by contacting your HR or payroll department to ask if they already have a salary packaging programme. Some organisations have exclusive arrangements with a single leasing company. However, many modern Australian employers allow a “choice of provider” model. This is where you gain the most leverage. By using a comparison service to find the most competitive quote, you can often save thousands over the life of the lease compared to a single-provider setup. You should also verify if your company has internal restrictions, such as:
- Caps on the vehicle’s purchase price or luxury car tax limits.
- Age limits on the vehicle (some employers only allow new or near-new cars).
- Specific requirements for insurance or maintenance providers.
Financial and Tax Bracket Assessment
The primary benefit of salary packaging is the reduction of your taxable income. If your annual salary sits just above a tax threshold, the lease payments could move you into a lower bracket, which effectively increases your take-home pay. You must also consider your HECS/HELP debt. While a novated lease reduces your taxable income, the “reportable fringe benefit” amount is used to calculate your compulsory HECS repayments. This doesn’t mean the lease isn’t viable, but it does mean your repayment obligations might increase. Including this in your novated lease checklist ensures you aren’t surprised by a lower than expected tax refund at the end of the financial year. Finally, confirm you are claiming the tax-free threshold with your primary employer to ensure your tax modelling is accurate.
The Documentation Checklist: Getting Quote-Ready
Securing a fast approval depends entirely on how well you prepare your digital filing cabinet. Most employees start by browsing car colours, but the real efficiency begins with gathering your financial evidence. To move quickly, your novated lease checklist must include your most recent pay slips. Usually, financiers require the last two or three consecutive cycles to verify your gross income and any existing salary deductions. This ensures the tax modelling is accurate from the first interaction.
You also need a clear copy of your Australian Drivers Licence, showing both the front and back. If you aren’t an Australian citizen, have your visa grant notice or a VEVO check ready to prove your residency status. These documents form the foundation of your credit application and allow the specialist to verify your identity immediately. Having this paperwork organised prevents the back-and-forth emails that often delay the settlement process by several days.
Personal and Financial Identification
Financiers conduct a thorough serviceability assessment that goes beyond your annual salary. You should prepare a basic summary of your monthly living expenses, including rent or mortgage repayments, utilities, and other credit obligations. It is wise to check your credit score through a service like Equifax or Experian before applying. A healthy file ensures you access the most competitive interest rates available. To satisfy the standard 100-point identification check required by Australian law, ensure you have your Medicare card or Passport on hand.
Vehicle-Specific Information Needed
The specific paperwork varies depending on whether you are eyeing a brand-new model or a used vehicle. For new cars, obtain a formal “pro-forma” invoice from the dealer. This document lists the purchase price, GST, and any fitted accessories. If you are looking at premium models, confirm the Luxury Car Tax (LCT) status. For 2026, the LCT thresholds are specific, and exceeding them can change the structure of your lease.
If you prefer a used or demonstrator vehicle, gather the registration number and a current odometer reading. Most providers have age limits for used cars, typically requiring the vehicle to be no older than 12 years at the end of the lease term. Once you have these vehicle details, you can use a novated lease calculator to model your potential tax savings before committing to a formal application. This proactive approach ensures you are comparing quotes based on real-world data rather than estimates.
Comparing Quotes: What to Look for in the Fine Print
Once you’ve gathered your documents, the next stage of your novated lease checklist is scrutinising the quotes you receive. It’s common to see a low weekly figure that looks attractive on the surface, but the devil is always in the detail. You must distinguish between the “Base Interest Rate” and the “Effective Interest Rate.” The base rate is essentially a marketing tool, while the effective rate accounts for all upfront and ongoing fees. If a provider refuses to disclose the effective rate, it’s a red flag that they might be hiding significant margins within the contract.
Look closely at the vehicle purchase price. Some providers include a “procurement fee” or “brokerage” fee within the car’s price. This can negate the fleet discount they claim to have secured for you. You should also evaluate the monthly management fees. These cover the administration of your account, but they vary wildly between providers and can add up to thousands over a five-year term. Finally, review the insurance premiums. Many Australian employees don’t realise they can often source their own comprehensive insurance rather than accepting the default policy bundled into the lease. Choosing your own insurer can often lead to better coverage at a lower price point.
The Three Pillars of a Quote Comparison
To conduct a true side-by-side novated lease comparison, you must look at three distinct areas. First is the finance component, which includes the interest rate and the residual value. Second, examine the running cost estimates. Ensure the quote uses realistic figures for fuel or EV charging, maintenance, and tyres based on your specific driving habits. Third, verify the tax savings. A transparent quote will clearly show the GST savings on the purchase price and the reduction in your taxable income. If these three pillars aren’t clearly defined, you aren’t getting the full picture.
Residual Value (Balloon Payment) Realities
The residual value is the final payment required at the end of the lease to own the vehicle outright. The Australian Taxation Office (ATO) sets strict minimum percentages for these values based on the lease term. For instance, a standard three-year lease typically requires a residual value of 46.88% of the purchase price. If a quote shows a significantly lower residual, the provider may be trying to artificially lower your weekly payments, which could lead to a breach of ATO guidelines. Always check the annual kilometre assumption in the quote. If you drive 20,000km a year but the quote assumes 10,000km, your running cost budget will be insufficient, leading to out-of-pocket expenses later. Including a check of these assumptions on your novated lease checklist prevents financial shocks at the end of your term.
Step-by-Step: The Approval and Settlement Process
Moving from the quote stage to the driver’s seat requires a methodical approach to settlement. Once you’ve finalised your provider from your novated lease checklist, you must submit a formal credit application to the financier. This is where your previously gathered pay slips and identification are scrutinised to ensure serviceability. Approval typically takes 24 to 48 hours, provided your financial documentation is accurate and complete. If you are self-employed or work for a small business, the financier might request additional bank statements to verify cash flow.
After credit approval, the leasing company will issue a settlement pack. This includes the finance contract, the payroll authority form, and the Novation Agreement. You must authorise your payroll department to begin deductions before the vehicle is delivered. These deductions are split into pre-tax and post-tax amounts to satisfy the Employee Contribution Method (ECM), which helps offset Fringe Benefits Tax (FBT) for petrol and diesel vehicles. The final step is vehicle delivery. Do not sign the final acceptance form until you have conducted a thorough inspection of the vehicle. Check the odometer, paintwork, and interior for any discrepancies against the dealer invoice.
The Novation Agreement Explained
The Novation Agreement is a tripartite document involving you, your employer, and the leasing company. The Deed of Novation is the legal transfer of lease obligations from the employee to the employer for the duration of your employment. This document is essential because it allows your employer to make payments on your behalf using your pre-tax salary. If you change jobs, the lease is “de-novated,” meaning the responsibility for the payments reverts to you as a standard finance lease. Most modern leases are portable, which means you can transfer the arrangement to a new employer who offers salary packaging without needing to pay out the lease early.
Setting Up Your Running Cost Account
Your lease includes a predetermined budget for fuel, maintenance, and tyres. You will receive a fuel card or, for electric vehicles, access to a dedicated charging network account to ensure you never pay for “fuel” with post-tax dollars. If you pay for car-related expenses out of your own pocket, you can submit a claim for reimbursement through your provider’s portal. For a deeper look at managing these budgets, read our guide on novated lease running costs. If you’re ready to start the process, you can get a competitive novated lease quote today to see your potential savings.
Maximising the 2026 EV Incentives
The final and perhaps most lucrative item on your novated lease checklist involves the strategic selection of an electric vehicle. As we move through 2026, the Federal Government’s Electric Car Discount continues to be the most significant driver of savings for Australian employees. By choosing a Battery Electric Vehicle (BEV) instead of a traditional internal combustion engine car, you can eliminate Fringe Benefits Tax (FBT) entirely. This exemption applies as long as the vehicle’s value remains below the Luxury Car Tax (LCT) threshold for fuel-efficient vehicles. Staying under this limit is critical. Exceeding it even by a small margin can trigger the full FBT liability, which negates a large portion of your tax savings.
Unlike previous years, the 2026 landscape is stricter regarding Plug-in Hybrid Electric Vehicles (PHEVs). While these were previously eligible for the exemption, the transition period has ended for most new arrangements, making pure BEVs the primary path to maximum tax efficiency. You should also look beyond the purchase price. A smart lease package in 2026 allows you to bundle the cost of a home charger installation. Including the charger in the pre-tax finance amount simplifies your setup and ensures your charging infrastructure is as tax-effective as the car itself.
FBT-Free Electric Vehicles in 2026
Choosing an FBT-free vehicle is a calculated financial move. On average, an EV novated lease in Australia can be A$3,000 to A$5,000 cheaper per year than a petrol equivalent of the same sticker price. This happens because every dollar of the lease payment, including running costs like electricity and tyres, is paid from your gross salary before tax is applied. To qualify, the car must be first held and used on or after 1 July 2022. For 2026, the LCT threshold for fuel-efficient vehicles is the figure to watch. If the retail price including GST and accessories stays below this mark, your take-home pay benefits significantly.
Using a Calculator for Accurate Modelling
Total savings vary based on your specific tax bracket and annual driving habits. High-income earners often see the most dramatic results; however, even those in middle brackets find that the FBT exemption makes premium EVs more affordable than entry-level petrol cars. You should use a novated lease calculator to input your exact salary and estimated annual kilometres. Adjusting these variables helps you find the sweet spot where your tax reduction is maximised against the vehicle’s residual value. This data-driven approach is the final step in completing your novated lease checklist and ensures your 2026 salary packaging deal is fully optimised for your personal circumstances.
Finalise Your 2026 Vehicle Strategy
Navigating the complexities of salary packaging doesn’t have to be a source of stress. By following this novated lease checklist, you’ve already taken the most important step toward financial optimisation. You now understand how to audit your eligibility, prepare your documentation, and peel back the layers of a quote to find the true effective interest rate. Whether you are aiming for the maximum tax savings of a 2026 electric vehicle or simply looking for a more cost-effective way to manage your daily drive, clarity is your greatest asset.
The marketplace is competitive, and you shouldn’t have to settle for the first quote your employer’s preferred provider offers. Our platform allows you to compare multiple providers in minutes, giving you the leverage needed to secure a superior deal. With expert Australian-based support and a high-accuracy 2026 tax savings calculator, we simplify the technical hurdles so you can focus on the road ahead. Get your competitive novated lease quotes today and start your journey with total confidence. You are now ready to drive away with a smarter deal.
Frequently Asked Questions
What are the minimum requirements for a novated lease in Australia?
To qualify, your employer must have a salary packaging policy in place and you must be a permanent employee. The vehicle can be new, used, or a demonstrator, provided it meets the financier’s age criteria. You’ll also need to meet standard credit approval requirements. Ensuring these basics are covered is the first step on any novated lease checklist before you start comparing specific vehicle models.
Do I need a permanent job to get a novated lease?
Financiers almost always require you to be a permanent full-time or part-time employee to ensure a stable income for the payroll deductions. Casual employees are generally ineligible because their hours and pay fluctuate too much for the fixed monthly lease payments. Additionally, most providers will require you to have completed your initial probation period before they’ll finalise a finance approval for your new vehicle.
Can I include a used car in my novated lease checklist?
You can certainly lease a used vehicle, but it must meet specific age and condition standards. Most providers require the car to be no older than 12 years at the end of the lease term. When adding a used car to your novated lease checklist, remember to gather the registration number, current odometer reading, and a dealer invoice to ensure the finance company can value the asset accurately before settlement.
What happens if I fail the credit check for a novated lease?
If your credit application is declined, the financier will provide a reason, which is often related to existing debt levels or a low credit score. You might be able to re-apply with a different lender or choose a less expensive vehicle to improve your serviceability ratio. It’s always a good idea to check your credit file through a service like Equifax or Experian before starting the formal application process.
Is insurance included in the novated lease checklist?
Comprehensive insurance is a mandatory part of the agreement and must be active before you take delivery of the car. While many leasing companies include a default insurance policy in their quotes, you aren’t usually obligated to use it. You can often save money by sourcing your own competitive policy and having the premiums bundled into your monthly salary sacrifice payments to maintain the tax benefits.
How long does the approval process typically take?
Credit approval is remarkably fast, typically taking between 24 and 48 hours once all your documents are submitted. The total time from your first quote to driving the car usually takes one to two weeks, depending on how quickly your employer signs the Novation Agreement. If you’re ordering a new car that isn’t currently in stock, the delivery timeline will depend on the manufacturer’s local supply and dealership timelines.
Can I get a novated lease if my employer doesn’t currently offer it?
You cannot start a novated lease unless your employer agrees to facilitate the payroll deductions. If they don’t currently offer it, you can suggest it to your HR department as a cost-neutral staff benefit. Many employers are happy to implement a programme once they realise it reduces their payroll tax obligations and helps with staff retention without adding any significant administrative costs to their bottom line.
What documents do I need to prove my income for a quote?
To verify your income, you’ll need to provide your two or three most recent consecutive pay slips. These documents allow the specialist to see your gross income, current tax withholding, and any existing deductions like HECS/HELP repayments. Providing clear, digital copies of these slips early in the process ensures your tax modelling is accurate and your credit approval moves forward through the system without any unnecessary delays.


