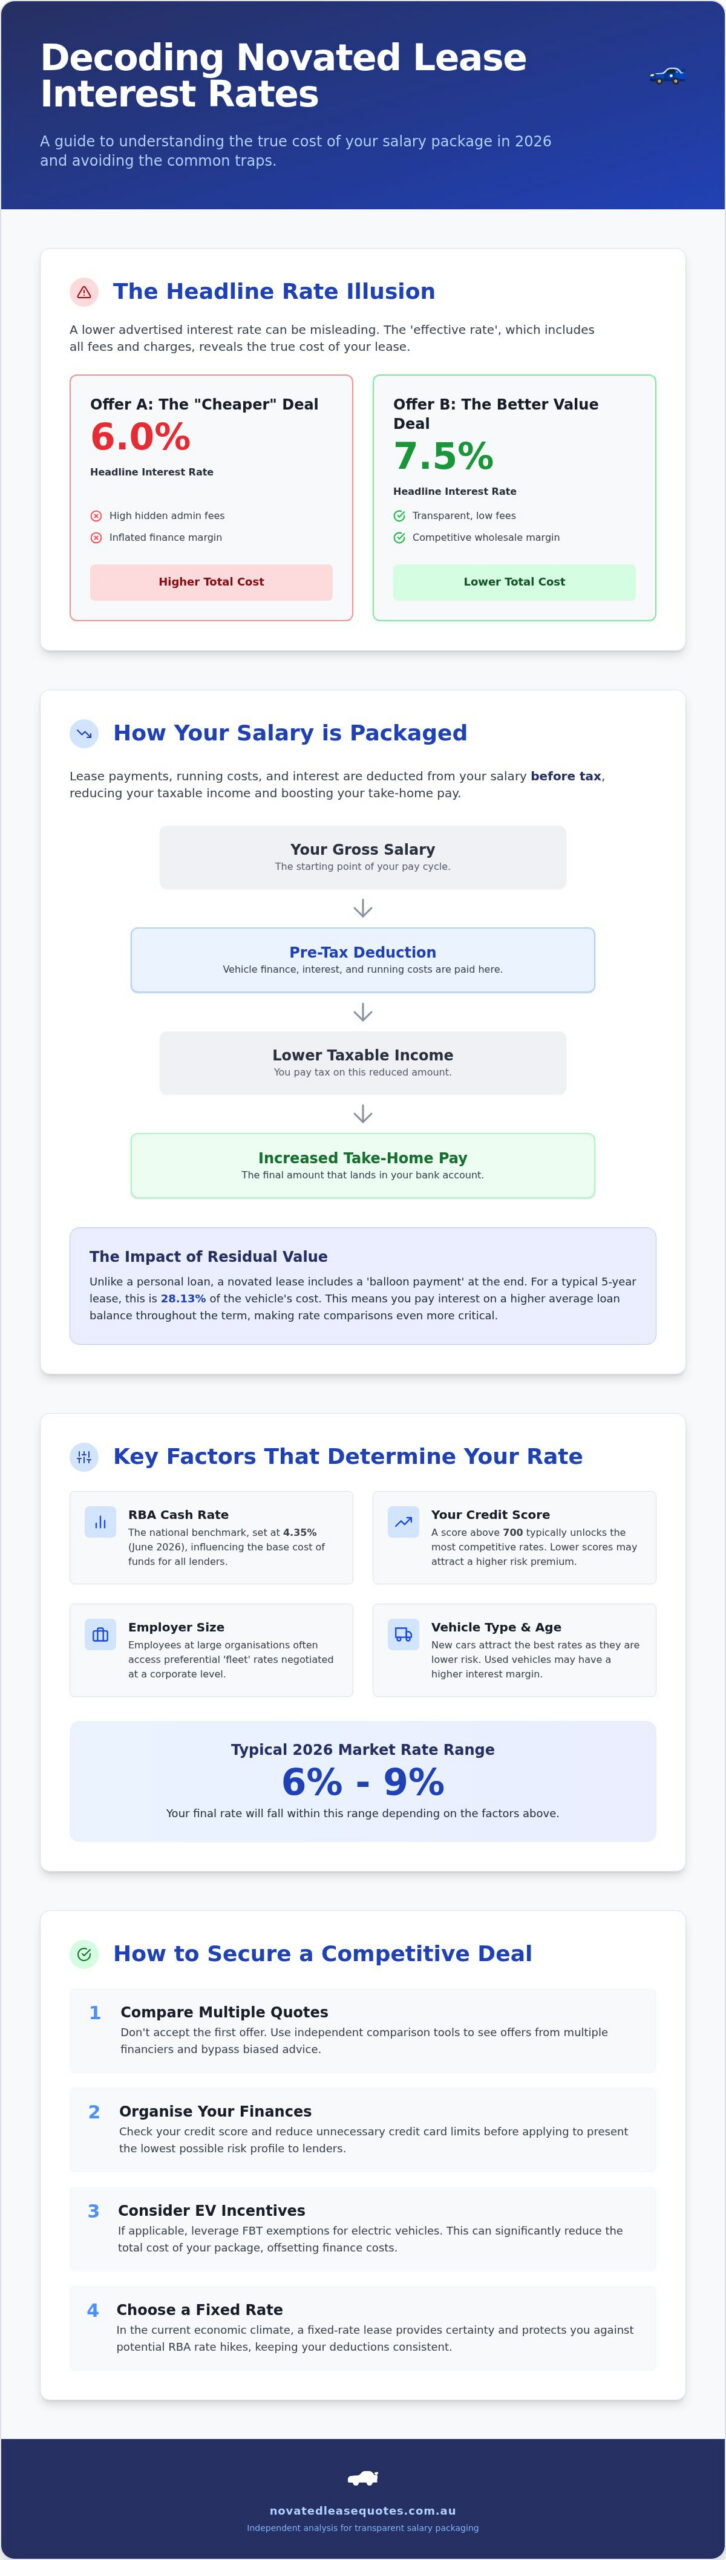
That 6% headline interest rate on your novated lease quote might actually be costing you more than a 7.5% offer from a competitor. It sounds counterintuitive, but in the 2026 Australian finance market, the base rate is often a distraction from the fees and structures that truly determine your monthly outgoings. You’re looking for a way to maximise your take-home pay through salary packaging, yet the lack of transparency in novated lease interest rates often makes it feel like you’re comparing apples with hidden lemons.
We understand that you want a clear, honest breakdown of what you’re actually paying. It’s exhausting trying to decode complex quotes when all you want is a reliable vehicle and a smaller tax bill. This guide promises to strip away the confusion, teaching you how to identify the most competitive offers currently available. We’ll examine how the 4.35% RBA cash rate sets the stage for today’s lending, distinguish between the base and effective interest rates, and provide a roadmap for using our specialised 2026 modelling tools to ensure your next lease is as cost-effective as possible.
Key Takeaways
- Learn how novated lease interest rates are applied across your pre-tax and post-tax salary components to calculate the true cost of borrowing.
- Understand the impact of the 2026 RBA cash rate and your individual credit score on the final finance margin you are offered.
- Recognise the difference between misleading “headline rates” and the effective interest rate to ensure you aren’t caught out by hidden fees.
- Discover how to use EV-specific incentives and multiple quote comparisons to drive down the total cost of your salary package.
- Master the process of using independent comparison tools to bypass biased advice and secure a transparent, competitive deal.
Understanding Novated Lease Interest Rates in 2026
The interest rate on a novated lease is the cost of borrowing for the vehicle’s finance component. In 2026, these rates are structured differently from standard retail loans because they are part of a tripartite agreement between you, your employer, and the financier. Understanding what is a novated lease? is essential to seeing how interest is applied across your salary package. Your interest costs are deducted from your gross salary along with your lease payments, which reduces your taxable income and changes the effective cost of the debt.
The presence of a residual value, or balloon payment, significantly impacts your total interest expense. Unlike a personal loan that you pay down to zero, a novated lease requires you to maintain a portion of the principal until the end of the term. For example, a five-year lease typically has a 28.13% residual value. Because you’re carrying this debt longer, you’ll pay interest on a higher average balance compared to a standard car loan, even if the novated lease interest rates look similar on paper.
Novated Lease vs. Car Loan Rates: A Comparison
You might notice that novated lease interest rates sometimes look higher than the headline rates offered by major banks for personal car loans. It’s a common trap to assume the lower rate is the better deal. The novated lease vs car loan comparison should always focus on the net impact on your bank account. By using pre-tax dollars to cover the interest and principal, you often end up with more take-home pay despite a slightly higher finance margin. You must look at the total cost of ownership to find the real winner.
The Role of the ATO and Interest Calculations
The Australian Taxation Office provides the framework for how these rates interact with your taxes. Fringe Benefits Tax (FBT) is calculated based on the vehicle’s value, but the interest you pay is part of the overall cost of providing the benefit. If you use the Employee Contribution Method, your post-tax payments help reduce your FBT liability to zero. The ATO’s benchmark interest rate provides a regulatory standard that ensures 2026 leasing contracts remain transparent and aligned with broader Australian economic conditions.
Factors Influencing Your Salary Packaging Interest Rate
The Reserve Bank of Australia (RBA) cash rate, which was held at 4.35% in June 2026, serves as the benchmark for all vehicle finance. While leasing companies don’t lend at this rate, it directly influences their cost of funds and the subsequent margins they pass on to you. In the current market, novated lease interest rates typically range from 6% to 9%, but where you land in that bracket depends on several variables beyond just the national economy.
Your employer’s size and the volume of their leasing programme also carry significant weight. Employees at large Australian organisations often benefit from ‘fleet’ rates. These are wholesale finance margins negotiated at a corporate level that an individual would struggle to access on the retail market. Additionally, the vehicle itself dictates the risk profile. New cars generally attract the most competitive rates because they represent reliable collateral, whereas used vehicles may carry a higher interest margin to account for faster depreciation and potential resale volatility.
Macro-Economic Drivers in 2026
The Australian finance market in 2026 has been shaped by a cautious approach to inflation, leading most employees to favour fixed-rate leases over variable options. A fixed rate provides protection against any late-year RBA hikes, ensuring your salary deductions remain consistent for the life of the contract. Timing your application is critical. Lenders often adjust their internal targets quarterly, so applying when a financier is looking to grow their portfolio can result in a more aggressive, lower-margin offer.
Credit Scores and Your Borrowing Power
Financiers use your credit report to determine the ‘risk premium’ added to your base rate. A credit score above 700 typically unlocks the most competitive leasing finance brackets in 2026. If your score is lower, or if you’re carrying significant existing debts like large credit card limits, the lender may view the application as higher risk. It’s a smart move to organise your finances and reduce unnecessary credit limits before you start the quote process. To see how your specific profile affects your monthly costs, you can request a tailored novated lease quote to compare current market offers.
Existing financial commitments, such as mortgages or personal loans, are also factored into your serviceability assessment. While these don’t always change the interest rate itself, they can impact the total amount a lender is willing to finance. By maintaining a clean credit history and demonstrating stable income, you position yourself as a ‘Tier 1’ borrower, which is the most effective way to drive down novated lease interest rates and maximise your take-home pay.
The Difference Between Headline Rates and Effective Interest Rates
A low headline rate is often the bait used to attract your attention, but it rarely tells the full story of your finance commitment. In the 2026 Australian market, many providers lead with a “base rate” that looks incredibly competitive while quietly recouping their margins through capitalised fees. This “Headline Rate” fallacy can lead you to believe you’ve secured a bargain when, in reality, your total outgoings are higher than a quote with a slightly higher percentage but fewer hidden costs. Understanding the nuances of novated lease interest rates requires looking past the bold text at the top of your quote.
Defining the “effective interest rate” is the only way to find the true cost of your finance. This figure accounts for every dollar you pay, including the interest margin, upfront brokerage fees, and ongoing monthly management charges. To reveal the real cost of any offer, you should use a specialised novated lease calculator. By inputting the total amount financed and the final monthly repayment, you can strip away the marketing jargon and see the actual percentage you’re being charged on the declining balance of your loan.
Unmasking Hidden Fees in Your Quote
Transparency starts with identifying “procurement fees” or “brokerage commissions” that are often added to the vehicle’s purchase price before the lease even begins. These fees are capitalised into the loan, meaning you pay interest on the fee itself for the next three to five years. Monthly administration or management fees are another common trap. While they might only look like A$20 or A$30 a month, they can add the equivalent of 1-2% to your interest rate over the life of the lease. Always ask your provider for a full disclosure of all finance-related costs before signing.
Comparing ‘Apples with Apples’
Real savings come from comparing the total amount financed rather than just the monthly repayment. Some providers may lower the monthly cost by extending the lease term or increasing the residual value, which actually increases the total interest you pay. You must also check if insurance premiums and running costs are bundled into the interest calculation. “Rate padding” is a common practice where complex salary packaging documents make it difficult to see where the finance cost ends and the service fees begin. By isolating the finance component, you can ensure that the novated lease interest rates you’re comparing are truly equivalent.
Practical Steps to Secure Competitive Interest Rates
Securing a competitive deal requires a proactive approach that goes beyond accepting the first offer from your employer’s preferred provider. You must create competition between financiers to drive down margins. Start by negotiating the purchase price of the vehicle as a cash buyer before you even mention finance. By locking in a lower vehicle price first, you reduce the total amount you need to borrow, which directly lowers the total interest you’ll pay over the life of the lease. Only once the car price is settled should you begin comparing novated lease interest rates from multiple sources.
The EV Advantage: Lowering the ‘Real’ Cost
In 2026, zero-emission vehicles offer a significant financial edge. Many Australian lenders now provide discounted ‘green’ finance rates specifically for eligible electric cars, often sitting at the lower end of the 6% to 7.5% range. When you factor in the EV novated lease Australia FBT exemption, the effective cost of your lease drops dramatically. Even if an EV carries a slightly higher interest rate than a petrol equivalent, the 47% saving on Fringe Benefits Tax usually makes the electric option far cheaper on a net-benefit basis. This tax structure effectively offsets the interest component, allowing you to drive a more expensive vehicle for a lower monthly out-of-pocket cost.
Negotiation Tactics for Australian Employees
Leverage is your best tool when finalising your finance. If you have a quote from one provider, use it to negotiate the brokerage fees and margins with another. Working with an independent specialist rather than a single-lender provider gives you access to a broader panel of financiers, increasing your chances of finding a Tier 1 rate. Before you commit, you should request a comparison of multiple novated lease quotes to ensure the offer on your desk is truly market-leading.
Your payroll department plays a vital role in this process. Before signing any documents, you should ask your payroll or HR manager these three specific questions:
- “Does our company policy allow for ‘choice of provider’ or am I restricted to a single panel?”
- “What internal administration fees does the company charge to facilitate this salary sacrifice arrangement?”
- “If I move to a different employer during the term, what are the specific requirements for porting this lease and its current interest rate?”
By getting these answers early, you can avoid restrictive agreements that might lock you into higher novated lease interest rates or unexpected administrative costs. Transparency with your employer ensures that the tax savings you’ve calculated actually hit your bank account every payday.
Comparing Quotes to Maximise Your Financial Outcome
Accepting the first quote you receive is rarely the best strategy in the Australian market. Leasing providers often lead with their most profitable margins, expecting that many employees won’t look further than the monthly repayment figure. However, even a marginal 0.5% difference in novated lease interest rates can save you thousands of dollars over a typical five-year term. When you consider that this interest is paid with a mix of pre-tax and post-tax dollars, the real-world impact on your take-home pay becomes even more significant.
Before you sign any agreement, you need to conduct a final review of the four pillars of a competitive lease. First, verify the effective interest rate, ensuring it includes all capitalised fees. Second, scrutinise the administration and management fees for any “padding”. Third, confirm that the residual value matches the ATO’s minimum requirements, such as 28.13% for a five-year term. Finally, check the flexibility of the contract. A truly competitive offer shouldn’t just have a low rate; it should also allow you to port the lease if you change employers or pay it out early without excessive penalties.
The Power of Independent Comparison
Novated Lease Quotes streamlines the process of finding the most competitive 2026 rates by providing an objective view of the marketplace. Instead of manually contacting multiple lenders and trying to decode different quote formats, our service allows you to compare offers side-by-side. Having experts review the fine print of your salary packaging agreement ensures that no hidden “procurement fees” or inflated service costs are eating into your tax savings. This transition from confusion to a data-backed financial decision is the most effective way to optimise your salary.
Next Steps: Get Your 2026 Quotes
Starting your comparison today is a straightforward process. To get an accurate interest rate quote, you’ll need to have your current gross salary details, your estimated annual kilometres, and the specific vehicle model you’re considering. Our online tools are designed to handle the heavy lifting, allowing you to see how different finance structures affect your weekly budget. Don’t leave your savings to chance by sticking with a single provider. You can request your competitive novated lease quotes now and take control of your vehicle finance with transparency and confidence.
Optimise Your Next Vehicle Purchase with Confidence
Securing a low-cost salary package in the 2026 market requires more than just a quick glance at a brochure. You now understand that novated lease interest rates are only one part of the calculation, with the effective rate and tax-saving structures like the EV FBT exemption playing a much larger role in your final take-home pay. By distinguishing between headline percentages and the true cost of finance, you’ve positioned yourself to avoid the common traps of hidden brokerage fees and inflated administration costs.
Efficiency is the key to financial optimisation. Instead of managing this complex process alone, you can leverage our independent and transparent comparison service to access a national network of leasing specialists. Our specialised 2026 savings calculator provides the clarity you need to make a data-backed decision that suits your unique budget. Compare competitive novated lease quotes and save in 2026 to ensure you aren’t overpaying for your next car. Smart financing is within your reach, and the savings you’ve identified today will benefit your bank account for years to come.
Frequently Asked Questions
What is a competitive novated lease interest rate in 2026?
A competitive comparison rate for a novated lease in 2026 generally falls between 6.5% and 7.5%. While the broader market range for novated lease interest rates spans from 6% to 9%, landing in the lower bracket depends on your credit profile and the vehicle type. It’s essential to look at the comparison rate rather than the base rate, as this includes mandatory fees and provides a more accurate picture of your actual finance costs.
Is the interest rate on a novated lease fixed or variable?
Most novated leases in Australia are structured with a fixed interest rate for the duration of the term, which usually ranges from one to five years. This provides certainty for your salary packaging deductions, ensuring your take-home pay remains consistent regardless of RBA cash rate fluctuations. While variable options exist, they are less common due to the complexity they add to payroll accounting and tax modelling for both employees and employers.
Can I negotiate the interest rate on my novated lease?
You can negotiate the finance margin and brokerage fees that make up your total interest cost. While the base lending rate is often set by the financier’s cost of funds, the markup applied by the leasing provider is usually flexible. The most effective way to negotiate is by presenting a competing quote from an independent comparison service, which forces providers to sharpen their margins and reduce upfront brokerage fees to secure your business.
Why is my novated lease interest rate higher than a mortgage?
Novated lease rates are higher than mortgage rates because they are secured against a depreciating asset rather than real estate. Cars lose value quickly, making them higher-risk collateral for lenders. Additionally, mortgages benefit from much longer terms and larger capital volumes. Vehicle finance is a specialised, shorter-term product with higher administrative requirements for the tripartite salary packaging agreements between the employee, employer, and the leasing company.
Does the interest rate affect my FBT-free EV savings?
Yes, the interest rate still impacts the total cost of an electric vehicle lease, even if it is FBT-exempt. While you don’t pay Fringe Benefits Tax on eligible EVs valued below the luxury car tax threshold of A$91,661, you are still paying for the finance. High novated lease interest rates will reduce your overall salary packaging benefit, though the 47% FBT saving typically remains the dominant factor in your total savings compared to a petrol vehicle.
Are there hidden fees on top of the quoted interest rate?
Many quotes include capitalised fees that aren’t immediately visible in the headline interest rate. These can include procurement fees, document fees, and monthly management charges. To find the true cost, you must calculate the effective interest rate, which accounts for all these charges. Always ask for a transparent breakdown of every fee that has been added to the vehicle’s purchase price or the monthly repayment to ensure full disclosure.
How does my credit score impact the interest rate I’m offered?
Your credit score is a primary factor in determining the risk premium a lender adds to your base rate. A score above 700 usually qualifies you for Tier 1 rates, which are the most competitive in the 2026 market. If your score is lower, lenders may move you into a higher-interest bracket or require a larger employee contribution to offset the perceived risk of the finance agreement, directly impacting your monthly take-home pay.


