Did you know that sticking with your hospital’s “preferred” leasing provider could be costing you thousands in hidden administration fees and uncompetitive interest rates? It’s a common trap for busy nurses, doctors, and allied health staff who don’t have the time to audit their salary packaging. You already work in a high-pressure environment where every cent of your hard-earned income counts, especially when you’re sitting in a high tax bracket and facing rising fuel costs. Securing a novated lease for healthcare workers shouldn’t feel like another administrative headache or a compromise on your financial freedom.
We understand that you want a new car with all running costs bundled into one simple payment, without the stress of overpaying. This 2026 guide reveals how you can leverage the current $91,661 Luxury Car Tax threshold and the ongoing FBT exemption for electric vehicles to significantly lower your taxable income. You’ll learn how to compare transparent quotes independently and ensure you’re getting the maximum GST savings available. We’ll walk you through the 2026-2027 tax brackets and show you why an independent comparison is the smartest move for your back pocket.
Key Takeaways
- Learn how a novated lease for healthcare workers utilises pre-tax salary to cover both your vehicle finance and all essential running costs.
- Discover why you aren’t restricted to your hospital’s preferred provider and how comparing independent quotes can lower your interest rates and fees.
- Capitalise on the 2026 EV incentives, including the FBT exemption for eligible vehicles priced below the $91,661 Luxury Car Tax threshold.
- Master the art of evaluating quotes by identifying the internal rate of return and leveraging fleet discounts to pay less than the retail price.
- Follow a simple, step-by-step checklist to confirm your eligibility and start the process of upgrading your vehicle with maximum tax efficiency.
What is a Novated Lease for Healthcare Workers?
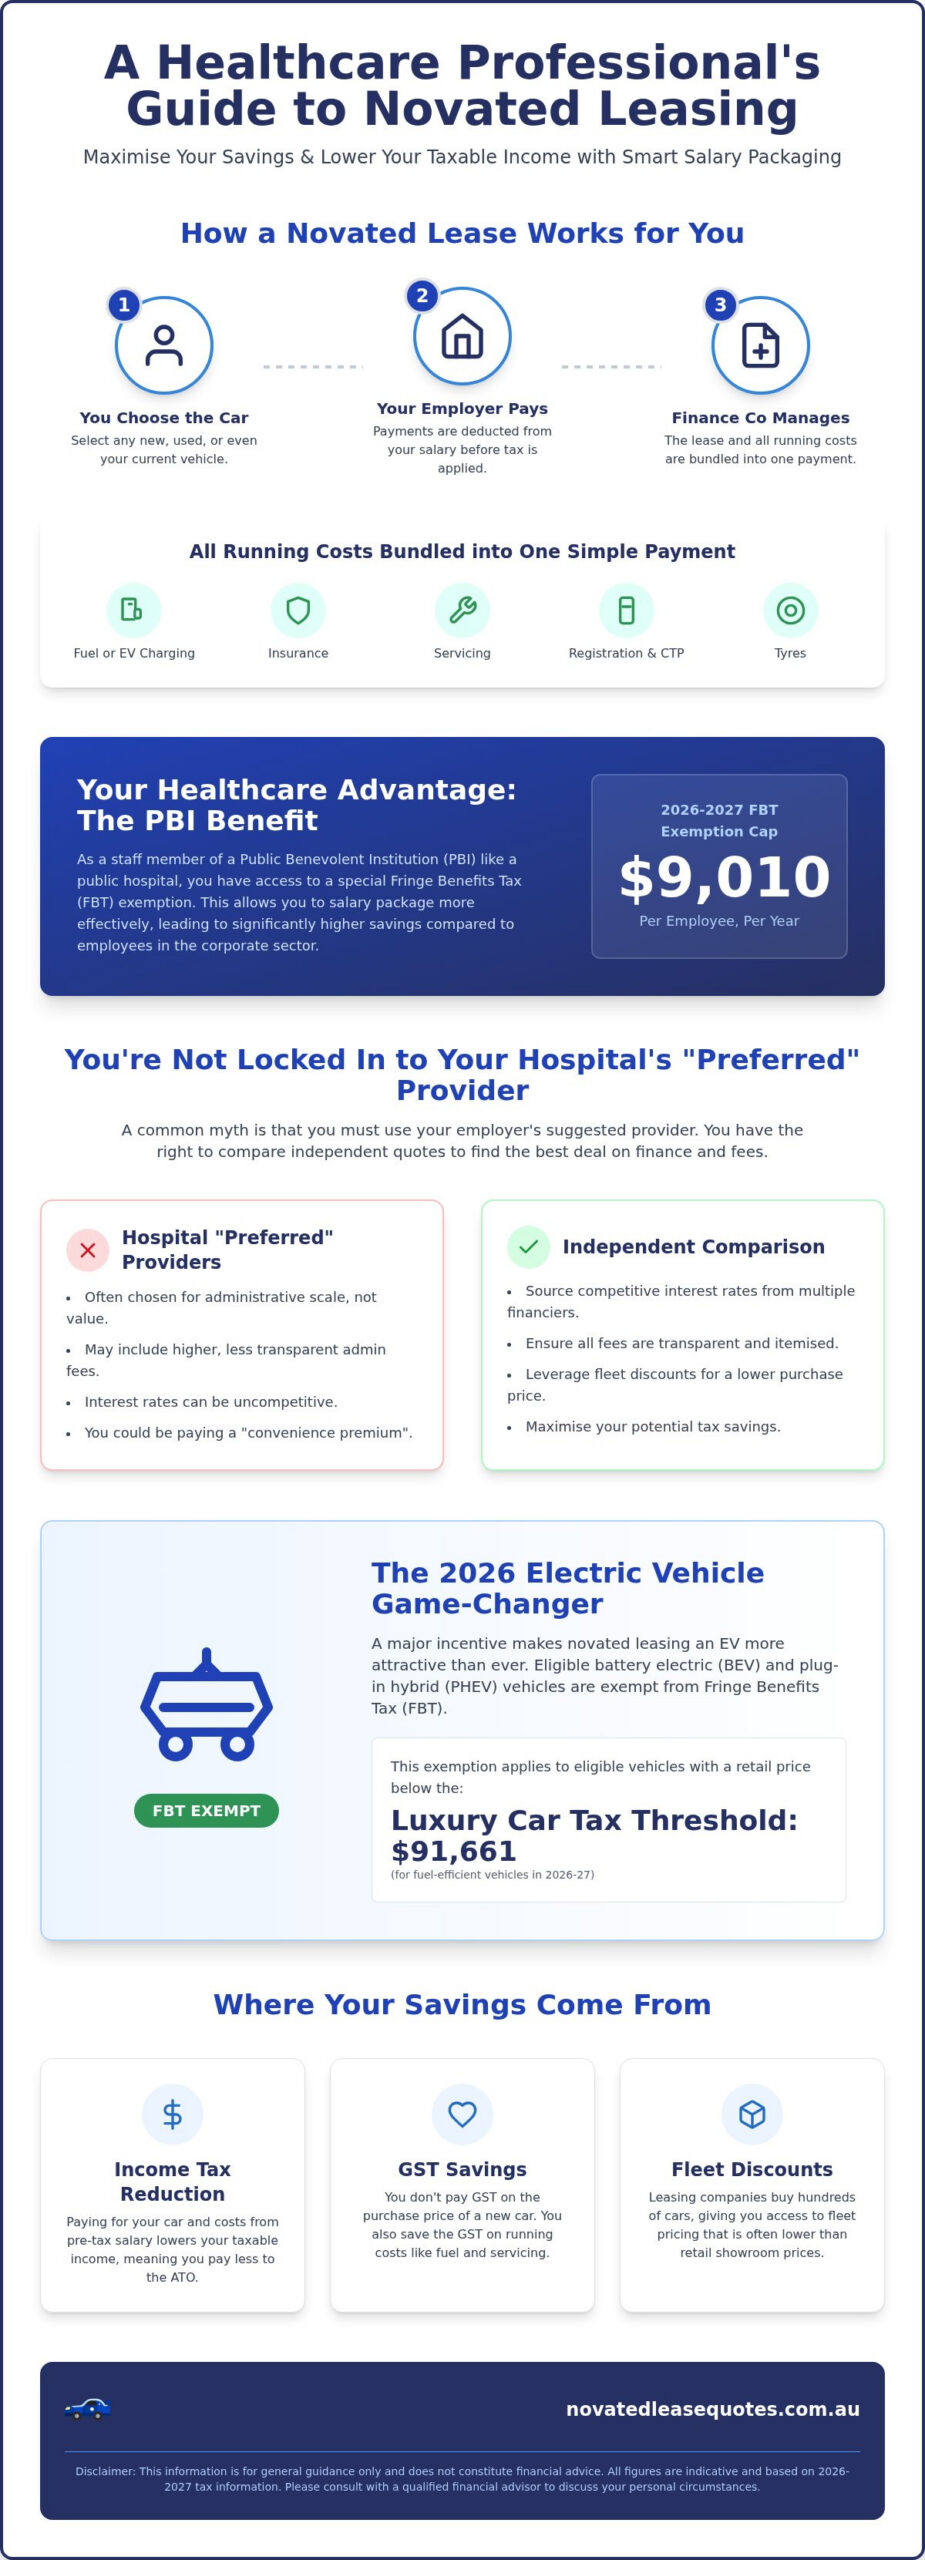
A novated lease is a financial arrangement that allows you to pay for a vehicle and its operating costs using your pre-tax income. It functions as a three-way agreement between you, your healthcare employer, and a finance company. For a nurse, doctor, or paramedic, this means your car repayments and all associated running costs are deducted from your salary before tax is calculated. This process reduces your taxable income, effectively putting more money back into your pocket every fortnight.
One of the biggest misconceptions about a novated lease for healthcare workers is that the car must be used for work purposes. This is not the case. The vehicle is yours to use for 100% private travel. Whether you’re commuting to the hospital or taking the family on a road trip, the tax benefits remain the same. In most scenarios, you won’t even need to maintain a complex logbook to justify the usage. It’s a simple, efficient way to manage a significant household expense.
The lease covers more than just the metal on the road. It bundles all your essential running costs into one predictable deduction, including:
- Fuel or electric vehicle charging costs
- Comprehensive insurance premiums
- Registration and CTP renewals
- Scheduled servicing and maintenance
- Replacement tyres and roadside assistance
The PBI Advantage: Why Healthcare is Different
Most public hospital and non-profit health staff work for what the ATO classifies as a Public Benevolent Institution (PBI). This status is a significant financial lever. PBIs enjoy a specific Fringe Benefits Tax (FBT) exemption cap, which for the 2026-2027 year remains at $9,010 per employee. This cap allows you to package various expenses, but using it for a vehicle is often the most efficient way to maximise your take-home pay. Because healthcare employers are often exempt from FBT up to this limit, the savings on a novated lease for healthcare workers are typically much higher than they would be for an employee in the private corporate sector.
Salary Sacrifice vs. Novated Leasing
It’s helpful to view a novated lease as a specialised branch of salary sacrifice. While you might already salary sacrifice your mortgage or rent, a lease is distinct because it bundles the asset and the operational costs into one deduction. This ensures you never have to pay for a service or a new set of tyres out of your post-tax savings. You can find more detail on these distinctions in our guide on Salary Sacrifice vs Novated Lease: Key Differences.
Can You Use Your Own Provider in Healthcare?
Many health professionals assume they must use the specific leasing company promoted in their hospital’s staff portal or induction pack. This is a persistent myth that can lead to missed savings. While your employer typically appoints a single Salary Packaging Administrator to manage payroll deductions, this is separate from the company providing the car and the finance. You often have the flexibility to select your own financier, which is where the real competition begins.
Seeking independent novated lease for healthcare workers quotes allows you to bypass the “one-size-fits-all” approach. Preferred providers are frequently chosen by hospital boards for their administrative scale, not necessarily because they offer the lowest interest rates or the most transparent fee structures. By looking outside the suggested list, you can often secure a more competitive deal that aligns better with your specific financial goals. Before committing, it’s worth comparing independent novated lease quotes to see exactly how much you could save on your monthly repayments.
Preferred Providers vs. Independent Quotes
Preferred providers often include procurement fees or higher interest margins that aren’t always visible at first glance. These costs represent the “convenience premium” you pay for using the default option. Healthcare workers have the right to compare finance to ensure they aren’t paying a convenience premium for an identical vehicle. When you find a better rate elsewhere, your Salary Packaging Administrator is usually required to facilitate the lease, provided the provider meets their basic compliance and insurance standards.
Self-Managed vs. Fully Managed Leases
Choosing between a fully managed or self-managed lease depends on your schedule and financial priorities. A fully managed lease is ideal for a time-poor nurse or surgeon. The provider handles all fuel cards, servicing invoices, and registration renewals. It’s a “set and forget” model. Conversely, a self-managed lease involves paying for running costs upfront and claiming them back through your administrator. This option often reduces monthly management fees and is popular with doctors who want maximum control over their cash flow and vehicle maintenance. Both paths offer the same core tax benefits, so the choice comes down to how much time you want to spend on administration.
Once you have an external quote that beats the preferred provider, simply present the offer to your HR or payroll department. Most public health departments are well-versed in handling third-party leases. They simply need the provider to coordinate with their chosen administrator to set up the pre-tax deductions. It is a straightforward process that could save you thousands over the life of your lease.
The 2026 EV Benefit: A Game Changer for Medical Professionals
The 2026 financial year represents a critical strategic window for healthcare staff looking to upgrade their vehicle. While the standard PBI tax-free cap remains a staple of medical salary packaging, the Federal Government’s Electric Vehicle FBT Exemption has become the most powerful financial lever available. This incentive allows eligible zero-emission vehicles to be completely exempt from the 47% Fringe Benefits Tax. For a novated lease for healthcare workers, this means you can pay for 100% of the car’s finance and all its running costs using your pre-tax salary without triggering a tax liability.
This benefit is particularly effective if you’re already maxing out your $9,010 PBI tax-free cap on mortgage or rent payments. Unlike other salary-packaged items, the EV FBT exemption sits outside that traditional cap. You aren’t forced to choose between saving on your home loan or saving on your car; you can effectively do both. By choosing a battery electric vehicle (BEV) priced below the $91,661 Luxury Car Tax threshold for fuel-efficient vehicles, you’re bypassing a significant portion of your income tax that would otherwise go to the ATO. If you are looking to use these savings to secure a new home or investment, you can visit Anna O’Neill Buyer’s Agent for professional property acquisition support.
Eligible Vehicles for Healthcare Workers
To qualify for these significant savings, the vehicle must be a battery electric or hydrogen fuel cell model. It’s important to note the shift in regulations for 2026. Plug-in hybrid electric vehicles (PHEVs) no longer qualify for the FBT exemption for any new leases entered into after 31 March 2025. This makes BEVs the primary choice for health professionals seeking maximum tax efficiency. When you select an eligible model, the impact on your take-home pay is substantial compared to a traditional petrol or diesel SUV. You can find a comprehensive list of qualifying models in our EV Novated Lease Australia: The 2026 Guide.
Charging and Running Costs
The savings don’t stop at the purchase price. A novated lease for healthcare workers allows you to package the installation of a home charging station and the electricity used for charging. This effectively replaces your petrol bill with pre-tax electricity costs. Because EVs have fewer moving parts than internal combustion engines, the long-term maintenance and servicing requirements are significantly lower. These reduced costs are also paid from your gross salary, ensuring that every dollar spent on keeping your car on the road is a tax-optimised dollar. As we approach the mid-2027 review of these exemptions, securing a lease now locks in these benefits for the duration of your term.
Evaluating Your Healthcare Novated Lease Quote
When you receive a quote for a novated lease for healthcare workers, it’s tempting to focus solely on the fortnightly deduction. Smart financial decision-making requires looking past the headline figure to understand the underlying mechanics. A transparent quote should clearly outline the interest rate, often expressed as an Internal Rate of Return (IRR), alongside all management fees and insurance premiums. Without this breakdown, it’s impossible to know if you’re getting a fair deal or paying for a provider’s high overheads.
One of the most significant benefits of this arrangement is the GST saving. You don’t pay GST on the purchase price of the vehicle, up to the $91,661 Luxury Car Tax threshold, nor do you pay it on running costs like tyres and servicing. Additionally, leasing providers access “fleet discounts” that are typically unavailable to individual buyers at a dealership. This means the “Amount Financed” should be lower than the retail price you see on the showroom floor. If your quote doesn’t reflect these institutional-level discounts, you’re leaving money on the table.
You also need to account for the residual value, or balloon payment, required by the ATO at the end of the lease term. For a standard five-year lease, the minimum residual is set at 28.13% of the purchase price. This is a future commitment you must plan for, whether you intend to pay it out, refinance, or trade the car in. Understanding how this figure is calculated ensures there are no surprises when your lease term concludes. To ensure you’re seeing the full picture, you should get a transparent quote comparison before committing to any single provider.
Hidden Costs to Watch Out For
Be vigilant about “origination fees” or documentation charges that can be buried in the fine print. Some providers also include inflated insurance premiums as a default. You often have the right to source your own comprehensive cover, which can be significantly cheaper than the “packaged” option. Always ask for a line-by-line breakdown of the amount being financed to ensure no unnecessary add-ons have been included without your express consent.
Using a Novated Lease Calculator
Before engaging with a salesperson, use an independent novated lease calculator to establish your baseline savings. These tools allow you to input your specific healthcare salary and tax bracket, such as the 30% rate for those earning between $45,001 and $135,000. This provides an accurate projection of the “Total Cost of Ownership” compared to a standard bank loan. It arms you with the data needed to challenge uncompetitive quotes and ensures your novated lease for healthcare workers is actually delivering the promised tax efficiency.
How to Get Started: A Simple Checklist for Health Staff
Moving from the research phase to actually driving your new car involves a few clear administrative steps. While the process is highly structured, paying attention to the details ensures you secure the best possible deal for your circumstances. Your first task is to confirm your employer’s specific salary packaging policy. Most public hospitals and health departments have an established framework, but you need to identify who their current Salary Packaging Administrator is. This is the entity that will handle your payroll deductions once the lease is active.
Next, you must select your vehicle. A novated lease for healthcare workers is not limited to brand-new showroom models. You can package a used car or even your current vehicle through a “sale and leaseback” arrangement. This allows you to unlock the equity in your existing car while still benefiting from pre-tax running costs. Once you have a vehicle in mind, obtain multiple novated lease quotes. Comparing different providers is the only way to ensure the interest rates and management fees are truly competitive.
After selecting the best quote, submit the documentation to your employer for approval. You will sign a novation agreement, which is the legal document that transfers the payment obligation to your employer for as long as you are on their payroll. Once the finance is settled and the paperwork is processed, you can pick up your car. From that moment, every tank of petrol, set of tyres, and rego bill is paid using your pre-tax income.
Documents You Will Need
Preparation reduces the time spent on back-and-forth emails with finance providers. To keep the process moving quickly, have the following items ready:
- Two or three recent payslips to confirm your current income and tax bracket.
- A copy of your current Australian driver’s licence and standard identity documents.
- The contact details of your hospital’s salary packaging or HR department.
The Role of Novated Lease Quotes
Our comparison service is designed specifically for busy professionals who don’t have hours to spend on car finance research. We streamline the entire journey by connecting you with a network of specialists who understand the unique payroll requirements of the Australian healthcare sector. This objective approach ensures you aren’t just taking the first offer from a preferred provider. You can get your obligation-free healthcare novated lease quotes today and see how the 2026 tax benefits apply to your specific situation.
Take Control of Your 2026 Salary Packaging
Your commitment to the healthcare sector should be matched by a financial strategy that maximises your hard-earned income. By securing a novated lease for healthcare workers, you can move beyond the restrictive “preferred provider” lists and find a finance structure that truly works for you. The 2026 EV incentives and the current FBT exemption rules represent a significant opportunity to lower your taxable income while driving a brand-new vehicle. Transparency is your most powerful tool; comparing independent quotes ensures you avoid hidden fees and uncompetitive interest rates.
We simplify this complex marketplace by offering an independent comparison of Australia’s top providers. Our specialists understand the specific PBI tax rules that apply to your profession, ensuring your salary packaging is fully optimised. You can access free, no-obligation quotes delivered straight to your inbox, allowing you to review your options without the pressure of a dealership environment.
Take the next step toward financial efficiency today. Compare Healthcare Novated Lease Quotes Now and discover the savings waiting for you.
Frequently Asked Questions
Is a novated lease worth it for a nurse on a mid-range salary?
Yes, a novated lease for healthcare workers is highly effective for those in the 30% tax bracket, which currently applies to incomes between $45,001 and $135,000. Even on a mid-range salary, you benefit from paying for your car and all running costs before tax is calculated. This reduces your taxable income and allows you to avoid paying GST on the vehicle’s purchase price and ongoing expenses like tyres and servicing.
What happens to my lease if I move from a public hospital to a private clinic?
Your novated lease is fully portable, meaning the vehicle stays with you when you change employers. You simply need your new employer to sign a novation agreement to continue the pre-tax deductions. It’s important to note that if you move from a Public Benevolent Institution (PBI) to a private clinic, the specific FBT treatment may change, so you should request an updated quote to see how your take-home pay is affected.
Can I include my existing car in a novated lease agreement?
You can package your current vehicle through a process known as a “sale and leaseback.” An Australian leasing specialist facilitates the purchase of your car at its current market value, and you then lease it back through your employer. This strategy allows you to unlock the cash tied up in your car while immediately transitioning your fuel, registration, and insurance costs to a tax-effective salary packaging arrangement.
Do I have to use the car for work travel to get the tax benefits?
No, there is no requirement for business-related travel to access the tax savings of a novated lease. The vehicle is intended for 100% private use, and you aren’t required to maintain a logbook for the ATO in most healthcare scenarios. Whether you’re driving to a night shift or taking a weekend trip to the coast, the tax benefits remain consistent regardless of your mileage or purpose of travel.
How does the EV FBT exemption change the savings for healthcare workers in 2026?
The EV FBT exemption is a significant driver of savings because it removes the 47% Fringe Benefits Tax on eligible zero-emission vehicles. For a novated lease for healthcare workers, this means you can package a battery electric vehicle (BEV) priced under $91,661 without it impacting your $9,010 PBI tax-free cap. This allows you to save on a car while still using your traditional cap for mortgage or rent payments.
What is the ‘residual value’ and how do I prepare for it?
The residual value is a final balloon payment required by the ATO to ensure the lease isn’t viewed as a simple purchase. For a five-year lease, the minimum residual is set at 28.13% of the original purchase price. You can prepare for this by either paying the amount to own the car outright, refinancing the residual into a new lease, or trading the car in and using the sale proceeds to clear the balance.
Can I package a used car if it’s from a private seller?
Yes, you can package a used car from a private seller, provided the vehicle meets the age requirements set by the financier. Most providers require the car to be no more than 10 to 12 years old at the end of the lease term. When buying privately, the leasing company will typically require an independent mechanical inspection and a valuation to ensure the car represents sound security for the finance agreement.
Does a novated lease affect my ability to get a mortgage?
Lenders view a novated lease as a financial commitment, similar to a personal loan or credit card. When you apply for a mortgage, the bank will factor the lease deduction into your cost of living and debt-to-income ratio. However, because a lease covers all your car’s running costs, many lenders acknowledge that you have fewer “out-of-pocket” expenses for transport, which can help balance your overall affordability assessment. If you’re looking to leverage your improved cash flow for specialised investments, consulting an NDIS property finance specialist Australia can help you secure the right funding for your long-term goals.