What if the most effective way to increase your take-home pay in 2026 isn’t a salary raise, but a change in how you pay for your car? Most Australian professionals feel overwhelmed by ATO jargon and the administrative hurdles of salary packaging. You probably worry that your HR department will find the request too complex or that a credit check will stall your plans. Mastering the novated lease application process australia doesn’t have to be a source of stress. It’s a structured path toward financial optimisation that any permanent employee can navigate with the right information.
We’ve designed this guide to help you move from confusion to confidence. You’ll learn exactly how to qualify for the latest tax breaks, including the 2026 FBT exemptions for electric vehicles and the updated Luxury Car Tax thresholds. We’ll provide a step-by-step roadmap of the application journey, from assessing your credit eligibility to pitching the idea to your employer. By the end of this guide, you’ll have the knowledge to select a vehicle that maximises your savings and the tools to manage the administrative side with ease.
Key Takeaways
- Understand why being a PAYG taxpayer is the fundamental requirement for accessing salary packaging benefits under ATO regulations.
- Learn how to effectively pitch the arrangement to your employer by addressing common myths regarding administrative complexity for small businesses.
- Identify which vehicles qualify for the best tax breaks, including the critical payload limits for dual-cab utes and 2026 EV criteria.
- Prepare for the financial assessment by understanding how lenders evaluate your credit history and take-home pay requirements.
- Master the novated lease application process australia through a clear, step-by-step roadmap that compares potential savings against traditional car loans.
Core Employee Eligibility Criteria: The Four Pillars
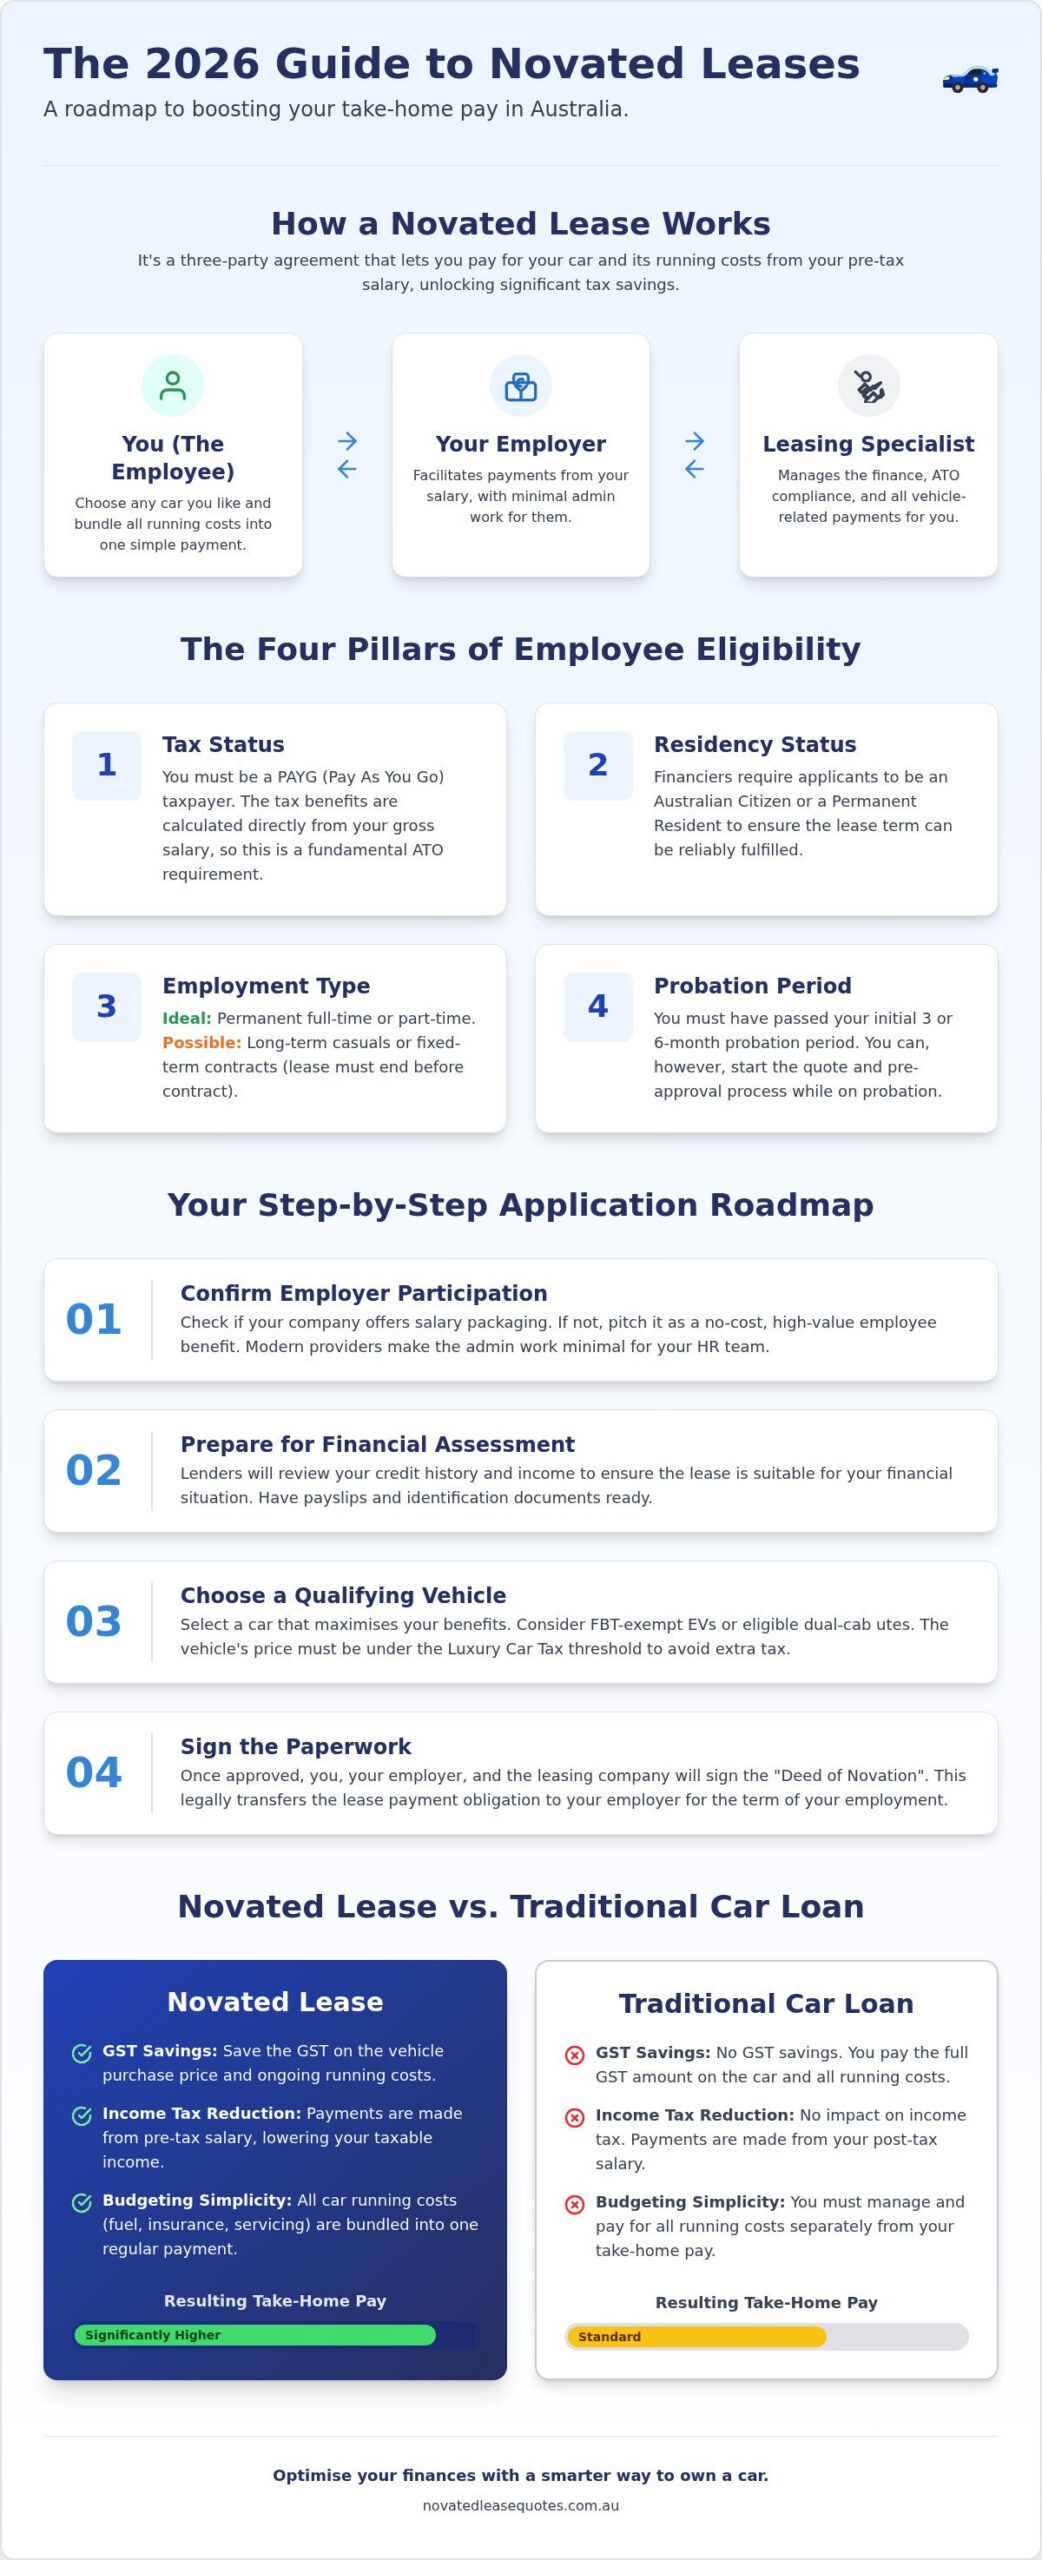
The foundation of any successful novated lease application process australia is your status as a PAYG (Pay As You Go) taxpayer. This requirement exists because the tax benefits are derived directly from your gross salary. If you’re a sole trader or a contractor who isn’t on a standard payroll, you can’t technically sacrifice salary you haven’t yet received as a PAYG employee. The Australian Taxation Office (ATO) sets strict guidelines for these arrangements, ensuring that the car is used primarily for private purposes while allowing the finance and running costs to be paid from your pre-tax income.
A novated lease is a three-party agreement between you, your employer, and the leasing specialist. Your employer agrees to deduct the lease payments from your salary and remit them to the specialist. This structure is what unlocks the GST savings on the vehicle’s purchase price and the subsequent income tax reductions. Your residency status also plays a role; financiers typically require you to be an Australian citizen or a permanent resident to ensure the lease term can be fulfilled without the risk of you leaving the country mid-contract.
Employment Status: Permanent vs. Casual and Contract
Permanent full-time and part-time roles are the gold standard for approval. Lenders value the stability of a recurring, predictable income. However, the common myth that casuals can’t apply is inaccurate. If you’re a long-term casual with “regular and systematic” hours, many financiers will consider your application, provided you can demonstrate a consistent history of earnings. For those on fixed-term contracts, the primary constraint is the lease duration. You’ll need to ensure the lease term doesn’t exceed your contract end date, as the employer’s obligation to pay ceases when your employment does.
Navigating the Probation Period Hurdle
Clearing your initial 3 or 6-month probation is a standard hurdle. Most financiers view the probation period as a high-risk window where employment could end abruptly. If you’ve just started a new role, don’t let this discourage you. Exceptions often exist for professionals moving between similar roles in the same industry with no significant gap in employment. You can still initiate the novated lease application process australia by requesting a quote during your first month. This pre-approval phase allows you to model your savings and have everything ready to execute the moment your permanent status is confirmed.
Employer Participation: Securing Your Company’s Approval
Before you dive into the novated lease application process australia, you must confirm that your employer is willing to facilitate the arrangement. While many large Australian corporations have established salary packaging programmes, employees in smaller businesses or startups often assume the option isn’t available to them. This is a common misconception. In reality, any business with a standard payroll system can support a novated lease. The perceived administrative burden is often the only thing standing between you and significant tax savings.
Modern leasing specialists have streamlined the process to the point where the employer’s involvement is minimal. They handle the calculations, the reporting, and the direct liaison with the financier. If your company doesn’t currently offer this benefit, your pitch should focus on the fact that it costs the business nothing to implement while serving as a powerful tool for employee retention. You can use a novated lease comparison to demonstrate how various providers manage the compliance and accounting side of the novated lease application process australia on the company’s behalf.
The Deed of Novation Explained
The core of this arrangement is the Deed of Novation. This legal document temporarily transfers the obligation of the lease payments from you to your employer. By signing this, your boss agrees to pay the lease costs using a combination of your pre-tax and post-tax salary. This structure is essential for accessing the GST credits on the vehicle’s purchase price and running costs as outlined in the ATO guidelines on novated leases. If you decide to change jobs, the deed is simply cancelled, the lease “re-novates” back to you, and you can potentially transfer it to your new employer’s payroll.
Internal Salary Packaging Policies
Every organisation has its own internal rules regarding salary sacrifice. It’s vital to check your HR manual for any specific restrictions. Some companies may limit the types of vehicles you can lease or require you to use a specific provider. You should also be aware of “Protected Earnings” regulations. Your employer will not allow you to sacrifice so much salary that your remaining take-home pay falls below a certain threshold. With the 2026 EV FBT exemptions now in full effect, it is a perfect time to request a policy update if your current manual doesn’t yet account for the significant savings available on zero-emission vehicles. To see how these exemptions affect your specific situation, you can start by requesting a tailored quote.
Vehicle Eligibility: What Cars Qualify in 2026?
Selecting a vehicle that meets specific regulatory criteria is a pivotal step in the novated lease application process australia. The ATO defines an eligible “car” as a motor vehicle designed to carry a load of less than one tonne and fewer than nine passengers. This strict definition excludes motorcycles and heavy commercial trucks. For those considering a dual-cab ute, the payload capacity is a critical metric. If the vehicle’s carrying capacity exceeds 1,000kg, it is generally classified as a commercial vehicle rather than a passenger car, which can alter the available tax benefits and finance options.
Financiers also impose age restrictions to protect the residual value of the asset. Most providers require the vehicle to be no older than 10 to 12 years at the end of the lease term. If you are eyeing a used car that is already eight years old, you might be limited to a two or three-year lease. While new cars offer the most straightforward approval path, used vehicles are increasingly popular for those looking to minimise their total amount financed while still enjoying the convenience of a packaged arrangement.
The 2026 EV and Hybrid Landscape
The 2026 market is heavily influenced by the Fringe Benefits Tax (FBT) exemption for zero-emission vehicles. To qualify for this 0% FBT rate, the car’s value must remain below the Luxury Car Tax (LCT) threshold for fuel-efficient vehicles, which is A$91,661 for the 2026-2027 financial year. For non-electric vehicles, the LCT threshold is lower, at A$80,809. It is vital to remember that plug-in hybrids (PHEVs) are no longer considered zero-emission vehicles for FBT purposes as of April 2025, unless a pre-existing commitment is in place. For a comprehensive look at these rules, see our EV novated lease Australia guide.
Used Car and Private Sale Restrictions
Purchasing through a registered dealer is the most efficient route for the novated lease application process australia. Dealers provide clear titles and tax invoices, which streamlines the financier’s settlement process. Private sales are possible but require additional inspections and more rigorous verification of the seller’s details to ensure the vehicle is free of encumbrances. If you already own a suitable vehicle, you may be eligible for a “Sale and Leaseback.” This involves selling your car to the leasing company at its current market value and then leasing it back, allowing you to access the same tax-effective running costs as a new lease.
Financial Assessment and Credit Score Requirements
A common misconception in the novated lease application process australia is that employer approval guarantees finance. While your company facilitates the payments, the financier enters into a contract with you as an individual. This means a comprehensive credit assessment is mandatory. Lenders evaluate your ability to meet the lease obligations after all other living expenses and debts are considered. They aren’t just looking at your salary; they are looking at your net disposable income to ensure the arrangement is sustainable for the duration of the term.
Your existing financial commitments play a significant role in this calculation. Obligations such as mortgages, personal loans, and even HECS/HELP debts are factored into your borrowing capacity. Under the 2026 Responsible Lending guidelines, financiers have become more methodical in verifying these details. They require a clear picture of your financial health to prevent “financial hardship” scenarios. To understand how your specific salary and expenses align with a potential lease, you should use a novated lease calculator to model your remaining take-home pay.
Credit Score Nuances for Australian Leases
A novated lease is typically recorded as a commercial hire purchase or a finance lease on your credit file. This differs slightly from a standard consumer car loan but still impacts your total credit limit. If you have a “thin” credit file with limited history, or a history of minor defaults, you may still be eligible, though you might face higher interest rates or stricter deposit requirements. The 2026 regulatory environment has slightly extended approval times, as lenders now perform more rigorous “look-through” assessments of bank statements to verify declared expenses.
The “Minimum Take-Home Pay” Rule
You cannot legally sacrifice 100% of your income. Financiers and the ATO require that you retain enough take-home pay to cover your basic cost of living. Lenders often apply the “Reasonable Food and Drink” test, which is a benchmark used to estimate your daily expenses based on your household size. If the lease payment pushes your remaining salary below these living expense benchmarks, the application will likely be declined. Balancing tax optimisation with your daily cash flow requirements is the most critical part of the novated lease application process australia. If you’re ready to see how these factors affect your eligibility, you can get a tailored quote comparison today.
Step-by-Step: The Novated Lease Application Roadmap
Once you’ve verified your eligibility and secured employer support, the actual novated lease application process australia follows a logical, five-stage progression. It’s designed to be efficient, moving from initial cost modelling to vehicle delivery in a structured manner that respects your time. Unlike a standard car loan, which only involves you and a lender, this roadmap ensures all three parties are aligned before the first deduction occurs.
- Step 1: Get a tailored quote. This is the baseline of your application. You’ll compare the “Worth It” factor of salary packaging against a standard car loan to see your actual tax savings.
- Step 2: Formal application and credit approval. You’ll submit your financial documentation for a credit assessment, as detailed in the previous section.
- Step 3: Employer setup. Your employer signs the Deed of Novation and integrates the lease into their payroll system.
- Step 4: Vehicle procurement and insurance. Your specialist finalises the purchase price with the dealer and organises your comprehensive insurance.
- Step 5: Delivery and deductions. You take delivery of the car, and your salary deductions begin on the next available pay cycle.
Gathering Your Documentation
To keep the novated lease application process australia moving quickly, you should prepare your “Application Pack” in advance. Financiers require recent payslips (usually the last two), a copy of your driver’s licence, and a letter or contract proving your permanent employment status. You’ll also need your employer’s ABN and the contact details for your payroll or HR manager. If you’ve already chosen a car, ensure you have a formal tax invoice from the dealer, as this is required for the financier to settle the funds and claim the GST credit on your behalf.
Finalising the Deal
The final stage involves signing the lease agreement and insurance documents, which most providers now handle via secure digital signatures. A critical component of this final pack is your novated lease running costs budget. This budget outlines your estimated spend on fuel or electricity, tyres, servicing, and registration. Once these figures are confirmed, they are locked into your salary sacrifice arrangement. When everything is signed and the employer has confirmed the payroll setup, the vehicle is settled and ready for pick-up. If you’re ready to start your journey, you can Get your competitive novated lease quotes now to see how much you could save.
Optimise Your 2026 Motoring Strategy
Navigating the novated lease application process australia is a strategic move for any permanent employee looking to increase their take-home pay. Success relies on aligning your PAYG status with a supportive employer and selecting a vehicle that meets the latest tax-saving criteria. Whether you’re targeting a zero-emission EV to leverage full FBT exemptions or seeking a traditional passenger vehicle below the updated Luxury Car Tax thresholds, the roadmap is structured and highly accessible.
The most effective way to start is by modelling your potential savings before you visit a dealership. Our platform offers an independent comparison of multiple Australian leasing specialists and expert support for 2026 EV FBT-free packaging. You can generate free tax-saving estimates with our national calculator to see exactly how a lease benefits your specific budget and disposable income.
Compare Novated Lease Quotes Today and take the stress out of your next vehicle upgrade. You’re now equipped with the eligibility insights needed to secure a smarter, more cost-effective deal on your next car.
Frequently Asked Questions
Can I get a novated lease if I am still on probation?
Most financiers require you to have completed your initial probation period, typically three to six months, before approving a lease. This ensures employment stability for the lender. However, if you’ve moved between similar roles in the same industry with no employment gap, some specialist providers may grant an exception. You can still begin the novated lease application process australia by requesting a quote during probation to prepare for your eventual approval.
Is there a minimum salary required for a novated lease in Australia?
There is no legal minimum salary requirement, but your income must be high enough to cover the lease payments and your essential living expenses. Financiers use “Protected Earnings” tests to ensure you aren’t sacrificing so much that your take-home pay becomes unsustainable. Generally, if you earn enough to be in a taxable income bracket, you can benefit from the arrangement, though the tax savings are more pronounced for higher earners.
Can I lease a used car from a private seller under a novated arrangement?
Yes, you can lease a used car from a private seller, though the process involves extra steps compared to a dealer purchase. The financier will require an independent mechanical inspection and a clear title check to ensure the car is free of existing debt. You must also provide a formal valuation to confirm the purchase price is fair. Buying from a registered dealer remains the most seamless path for most applicants in the current market.
What happens to my lease eligibility if I change jobs in 2026?
If you change jobs, your current novated lease agreement is temporarily paused and the responsibility for payments “re-novates” back to you personally. You can then transfer the lease to your new employer’s payroll, provided they agree to the arrangement. This portability is a key feature of the novated lease application process australia, allowing you to maintain your tax-effective car payments even as your career progresses or you move between different organisations.
Are casual employees ever eligible for salary packaging a car?
Casual employees face higher hurdles but aren’t strictly excluded if they have “regular and systematic” hours. Most lenders require at least 12 months of consistent employment history with the same company to prove income stability. If your hours fluctuate significantly, financiers may view the application as high risk. Permanent part-time or full-time roles remain the preferred employment status for a straightforward approval and access to the most competitive interest rates.
Does my employer have to be a large company for me to qualify?
Your employer does not need to be a large corporation or a government entity to qualify. Any Australian business with a standard PAYG payroll system can facilitate a novated lease. Many small to medium enterprises (SMEs) use external leasing specialists to handle the administrative side, which removes the burden from their internal accounts team. If your boss is willing to sign the Deed of Novation, you can proceed regardless of company size.
Can I have two novated leases at the same time?
You can certainly have two novated leases simultaneously, provided your net take-home pay satisfies the financier’s affordability criteria. This is common for households where one person packages two vehicles for family use. Each lease is assessed individually for credit approval, and you must ensure that the combined sacrifice doesn’t breach the “Protected Earnings” threshold set by your employer or the responsible lending guidelines followed by the finance provider.
Does a novated lease affect my ability to get a home loan?
A novated lease will impact your home loan borrowing capacity because banks view the lease payment as a fixed monthly commitment. While the lease reduces your taxable income, which might seem beneficial, the lender focuses on your net disposable income. However, since a lease often covers all running costs like fuel and insurance, it can sometimes be viewed more favourably than a standard car loan plus separate, unmanaged out-of-pocket expenses for vehicle maintenance.


